+971-8000321216


Key Takeaways:
- AI can connect the entire mortgage lead journey from lead capture and qualification to follow-up, application, and funded-loan tracking.
- Dynamic lead scoring and intelligent routing help mortgage teams prioritize prospects based on engagement, intent, location, loan type, and configured business rules.
- Human oversight remains essential when AI generates recommendations, borrower communications, or workflow decisions that require professional judgment.
- CRM, LOS, communication, calendar, and analytics integrations are important for maintaining connected borrower data and reducing duplicate manual work.
- Development costs can range from $25,000 to $200,000+, depending on AI capabilities, integrations, security requirements, communication channels, data migration, and overall platform complexity.
Want similar results? → Get a Free Quote
Mortgage buyers rarely move through a simple straight-line journey. A person may discover a lender through an ad, then return days later through a website form after the first interaction. But without a proper system in place, these signals would be spread out all over the place, and the opportunity would be missed.
Moreover, this is a much bigger problem when you consider how large this industry is. As per a report, the mortgage lending industry is projected to reach $41,833.26 billion by 2035, growing at a 9.0% CAGR from 2025 to 2035. With thousands of clients managed by lenders and brokers via several campaigns, knowing who you should reach out to next could matter just as much as generating more leads.
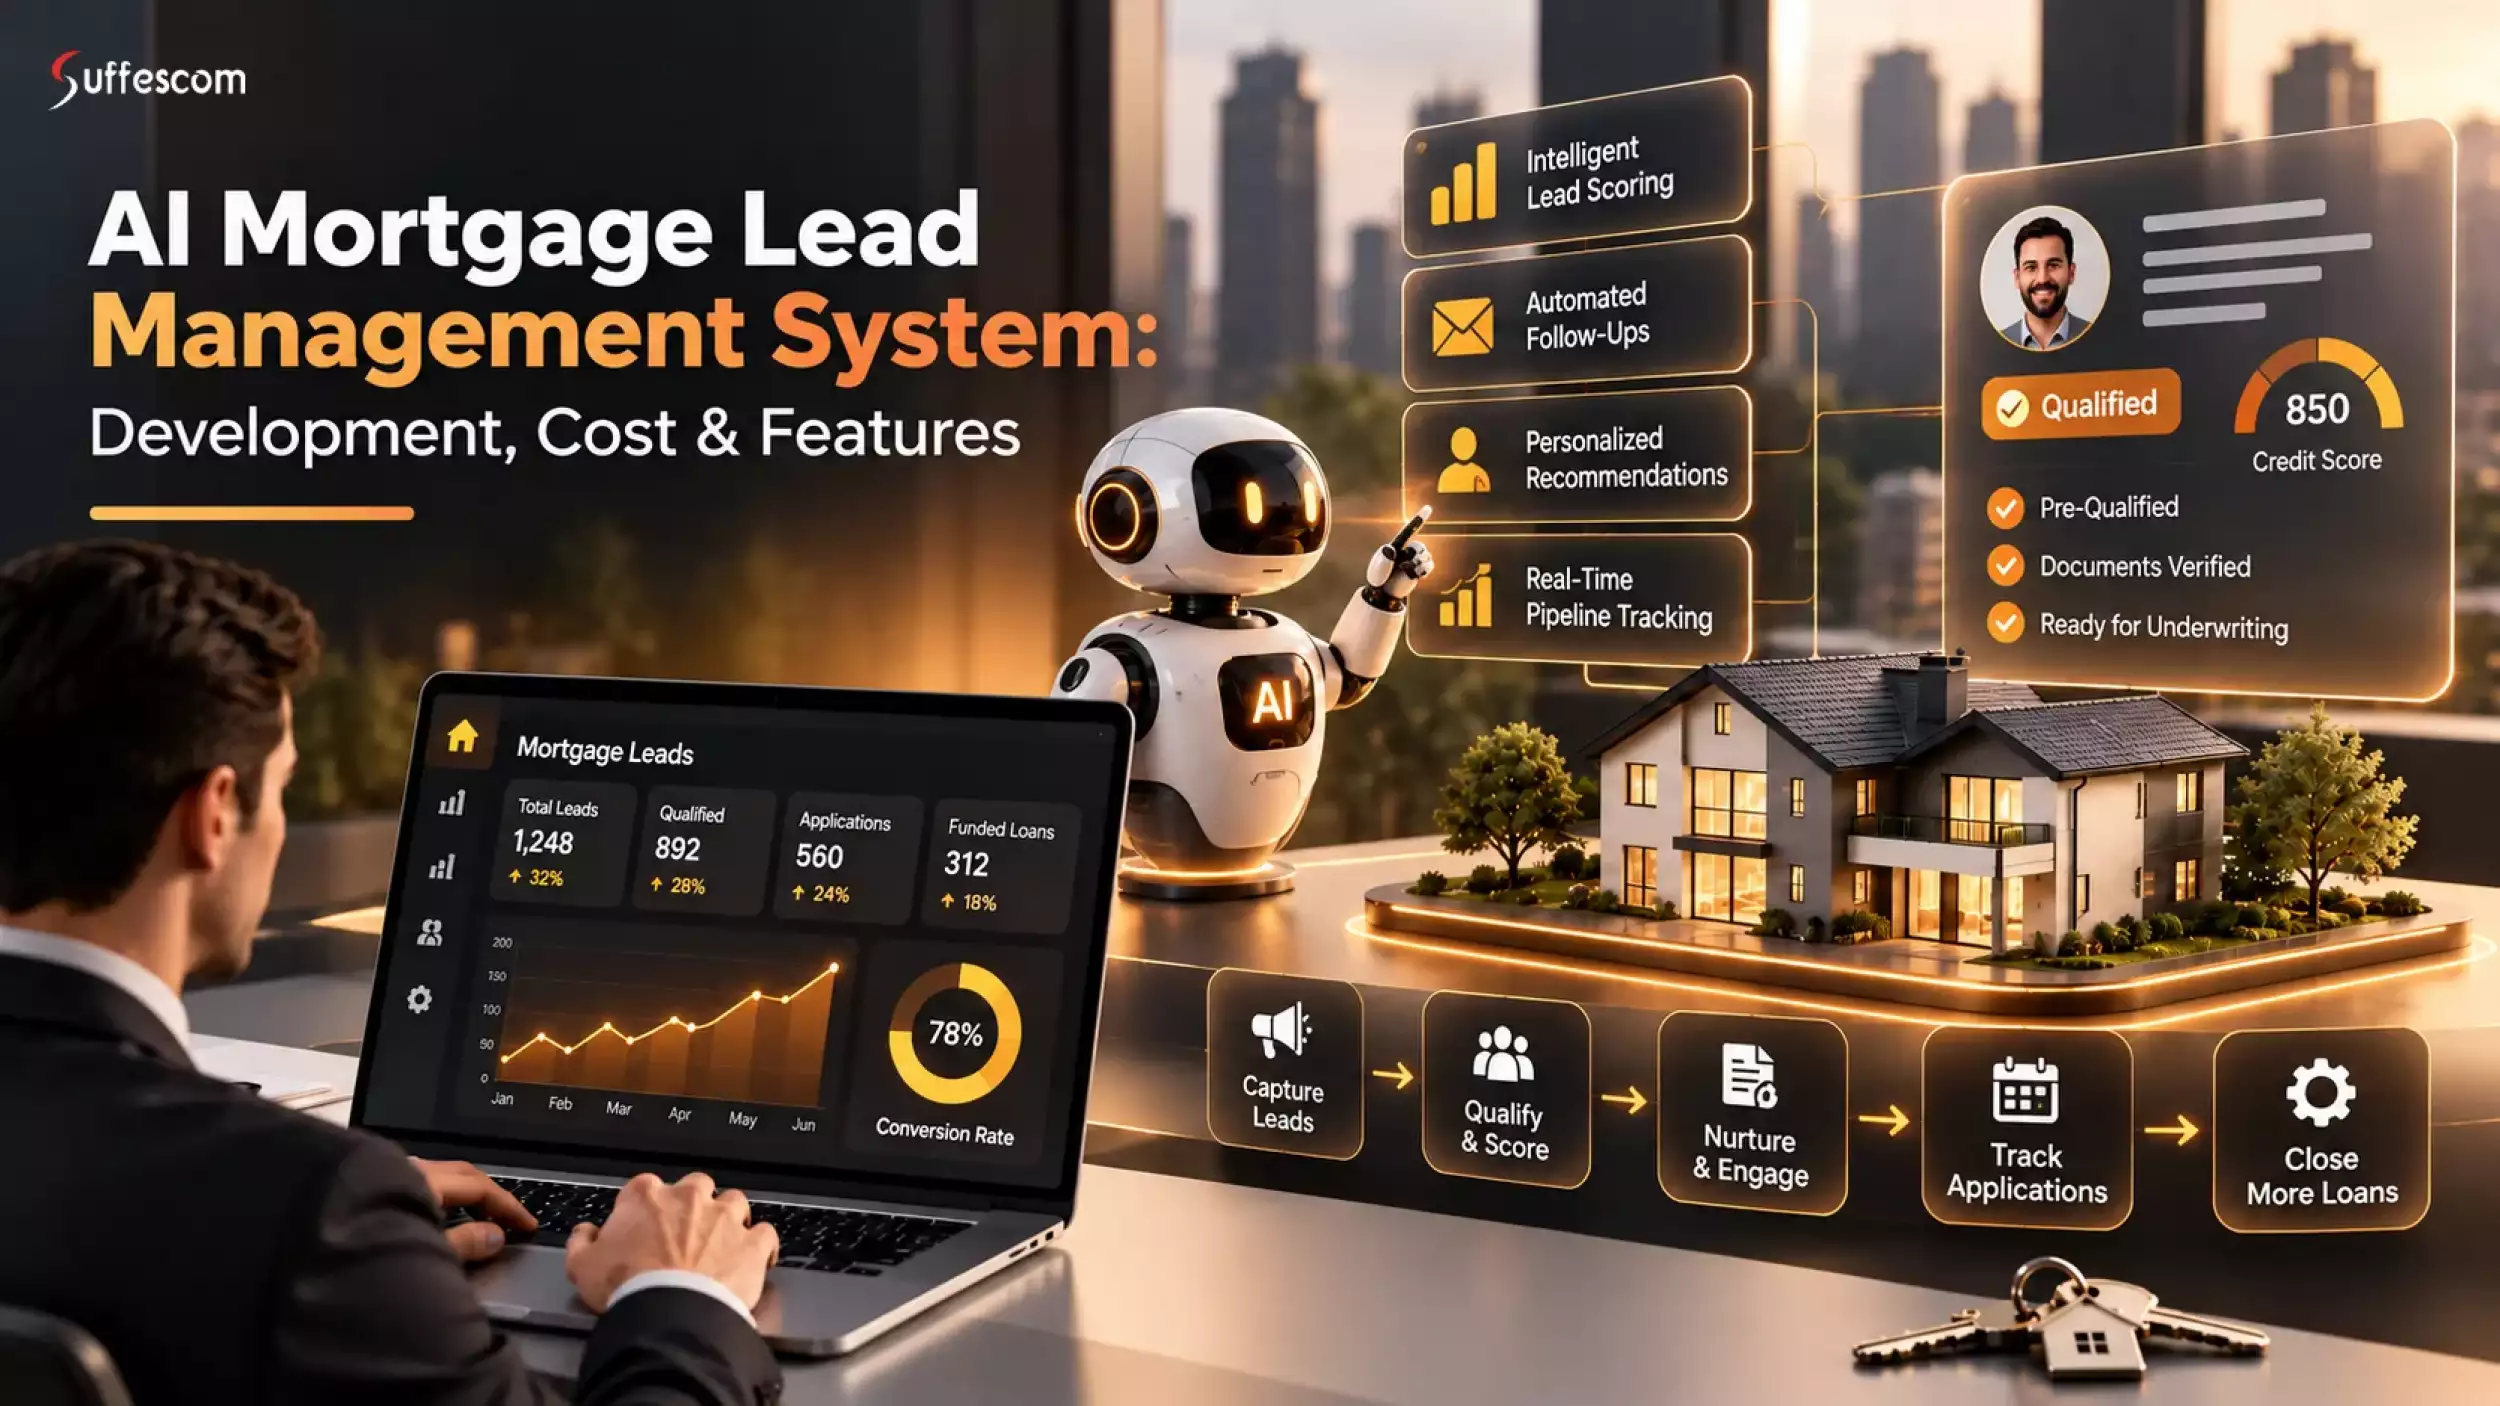
An AI mortgage lead management system development approach connects these moving pieces through intelligent lead capture, qualification, scoring, routing and nurturing. This way, it can convert borrower signals to usable information and give loan officers the necessary context at the correct time.
This guide explores what goes into building such a platform, which includes its AI capabilities, security controls, and other metrics.
What Is an AI Mortgage Lead Management System?
An AI mortgage lead management system is a software platform that helps lenders and mortgage teams collect, organize and act on prospect data throughout the sales journey. It connects lead sources with CRM workflows and AI capabilities so teams can identify relevant signals and determine what action should happen next.
Unlike a basic lead database, the system can analyze borrower interactions across forms, emails, calls, website activity and campaigns. It can then assist with qualification and recommend follow-up actions while keeping loan officers involved in important borrower interactions.
For example, a prospect who again and again checks purchase loan content and returns to a mortgage calculator could receive a higher engagement signal than someone who submitted a form but has shown no activity afterwards. The system can surface that context to a loan officer instead of treating both prospects as identical records.
AI Mortgage Lead Management System vs Traditional Mortgage CRM
A traditional mortgage CRM only stores borrower information and helps teams handle predefined sales workflows. An AI enabled platform adds an intelligence layer that can interpret activity and support decisions.
| Capability | Traditional mortgage CRM | AI mortgage lead management system |
| Lead capture | Stores incoming leads | Captures and structures lead data from multiple sources |
| Qualification | Rule-based fields and manual review | AI-assisted information extraction and qualification |
| Prioritization | Static lead scores | Dynamic scoring based on defined signals |
| Follow-up | Preconfigured workflows | Context-aware recommendations and automation |
| Lead routing | Fixed assignment rules | Routing based on configurable business signals |
| Conversation analysis | Limited or manual | AI-assisted analysis of calls and messages |
| Reporting | Historical dashboards | Real-time insights and predictive analytics |
| Human involvement | Primarily manual | Human review at defined decision points |
The distinction is important during development. AI should support the mortgage team's workflow rather than be treated as a replacement for licensed professionals or compliance controls.
How AI Changes Mortgage Lead Management
AI introduces a layer between raw lead activity and the actions taken by a mortgage team. Instead of relying only on static fields such as loan type or location, the system can process behavioral and conversational signals to provide additional context.
Common applications include:
- Data extraction: Converting information from forms and conversations into structured CRM fields.
- Lead prioritization: Identifying prospects showing stronger engagement or purchase intent.
- Conversation intelligence: Summarizing calls and extracting relevant follow-up information.
- Next-action recommendations: Suggesting whether a lead may need a call, message, appointment or human review.
- Nurturing assistance: Selecting relevant communication workflows based on lead status and engagement.
- Performance intelligence: Connecting lead activity with downstream outcomes such as applications and funded loans.
AI outputs should remain explainable for users to know why a lead received a particular recommendation. This becomes very important when AI influences workflows involving prospective borrowers.
Who Needs an AI Mortgage Lead Management Platform?
The platform can serve mortgage businesses with different lead volumes and operating models.
Mortgage lenders can use it to centralize leads from marketing campaigns and branch operations while giving loan teams a shared view of prospect activity.
Mortgage brokers can manage leads across different loan products and referral channels while configuring routing based on their brokerage workflow.
Mortgage marketplaces can connect incoming borrower requests with appropriate lending partners through configurable routing workflows.
Fintech startups can use an AI-enabled lead layer as part of a broader digital mortgage platform without relying entirely on manual sales operations.
Mortgage marketing agencies can use lead intelligence and attribution data to understand how campaign-generated prospects progress through the mortgage funnel.
AI Mortgage Lead Management Workflow
The main workflow connects lead acquisition with sales activity and outcomes. Instead of treating lead management as a collection of isolated CRM tasks, the system creates a continuous data flow.
| Stage | Traditional approach | AI-enabled approach |
| Lead capture | Data entered into CRM | Leads captured through forms, APIs and connected channels |
| Data preparation | Manual record cleanup | Automated validation and enrichment |
| Qualification | Loan officer reviews each lead | AI extracts relevant signals for review |
| Prioritization | Static rules | Dynamic scoring based on configured signals |
| Assignment | Fixed routing rules | Context-aware routing using business rules and available signals |
| Engagement | Manual follow-up | Triggered workflows with AI-assisted personalization |
| Sales activity | Notes entered manually | AI-assisted summaries and activity capture |
| Outcome tracking | Periodic reporting | Funnel monitoring tied to downstream outcomes |
Why Mortgage Businesses Are Investing in AI Lead Management Software
Mortgage lead management is becoming a data and timing challenge. Leads can arrive from paid campaigns, referral partners, websites and marketplace platforms at different points in the borrower journey. Managing those opportunities manually makes it harder to identify which prospects need attention and when.
AI mortgage software solutions give lenders and brokers a way to connect these interactions with their sales process. The investment case is not simply about adding AI. It is about reducing avoidable delays, improving visibility and helping mortgage teams make better use of the leads they already generate.
The Speed-to-Lead Problem in Mortgage Sales
The first response can influence whether a prospect continues the conversation with a lender. A Harvard Business Review study found that companies responding to leads within an hour were 7 times more likely to qualify the lead than those that responded within the next hour.
Mortgage teams face an additional challenge because leads can arrive outside normal working hours. An AI mortgage CRM can acknowledge an inquiry immediately and trigger the appropriate workflow while keeping the loan officer responsible for substantive borrower discussions.
The relevant metric is not simply response time. Businesses should also measure whether faster responses improve:
- Lead-to-contact rate
- Contact-to-conversation rate
- Appointment rate
- Application rate
- Funded-loan rate
Rising Demand for Personalized Borrower Communication
Borrowers interact with lenders through multiple digital touchpoints before speaking with a loan officer. A generic message may not reflect where someone is in the mortgage journey.
AI can help organize available interaction data so communication is more relevant to the prospect's context. For example, a borrower researching refinancing can enter a different nurture workflow from someone exploring their first home purchase.
Personalization should still operate within defined communication rules. The system should not generate unsupported claims about loan eligibility or make decisions that require qualified human review.
Reducing Lead Leakage and Missed Opportunities
Lead leakage can happen when an inquiry remains unassigned, a follow-up task is forgotten, or an inactive prospect disappears from the sales pipeline.
A mortgage lead management platform can monitor pipeline activity and identify records that require attention. Instead of relying solely on individual reminders, teams can establish workflow triggers for events such as:
- Unassigned leads
- Missed follow-ups
- Unanswered inquiries
- Repeated website engagement
- Expiring nurture sequences
- Dormant high-value prospects
This gives managers a measurable way to identify where leads are being lost instead of assuming that increasing lead volume will solve the problem.
Managing Leads Across Multiple Channels
Mortgage lead generation software often needs to handle data from several acquisition channels. A prospect may first arrive through a paid advertisement and later interact through a website form or phone call.
Without a connected data layer, these interactions can create duplicate records and fragmented histories.
An AI mortgage lead management system can consolidate channel activity into a unified prospect record. Developers should define identity resolution rules during implementation so duplicate records do not distort lead scores or conversion reporting.
Useful channel-level metrics include:
| Metric | What it reveals |
| Leads by source | Which channels generate demand |
| Qualified leads by source | Which channels produce relevant prospects |
| Cost per qualified lead | Acquisition efficiency |
| Application rate | Down-funnel lead quality |
| Funded-loan rate | Business outcome by source |
| Revenue per lead | Commercial value of each channel |
Improving Loan Officer Productivity
Loan officers can spend substantial time performing repetitive administrative tasks such as reviewing lead records, updating notes and preparing follow-up activities.
AI mortgage sales automation can reduce some of this workload by generating call summaries, extracting structured information and organizing follow-up tasks. The objective is to give loan officers more usable context without removing their control over borrower interactions.
A practical productivity measurement framework can compare:
Administrative time per lead → Contact time per lead → Qualified leads handled per officer → Applications managed per officer
This provides a more meaningful assessment than measuring the number of AI-generated messages or automated tasks alone.
Automate Your Mortgage Lead Workflow
Connect lead capture, qualification, routing, nurturing, and conversion tracking with an AI-enabled platform built around your sales process.
How an AI Mortgage Lead Management System Works
An AI mortgage lead management system connects lead generation with qualification and sales performance monitoring. In each case, more details are added to the lead record for mortgage specialists to determine how to proceed further.
Step 1: Capture Leads From Multiple Sources
The platform receives leads from websites, marketplaces, email, and many other sources. APIs and webhooks can send records to the central lead management system.
Step 2: Clean and Enrich Lead Data
Incoming records are validated to identify missing fields, duplicate entries, and inconsistencies. The platform can then organize the collected borrower and engagement data about borrowers and their engagement into a lead profile.
Step 3: Use AI to Qualify Mortgage Prospects
Artificial intelligence can examine the gathered information and behavior to spot signs of purchase intention, timing, and engagement level. The output should support loan officer review rather than make lending decisions.
Step 4: Score Leads Based on Intent and Fit
A score is generated based on configurable business rules and behavioral cues. The score can help the team prioritize follow-up without losing sight of the reasoning behind the recommendation.
Step 5: Route Leads to the Right Loan Officer
Routing rules can consider factors like location and licensing requirements. The system then assigns or recommends the appropriate loan officer.
Step 6: Trigger Personalized Follow-Ups
Using criteria like status of leads and communication permission settings, the system sends follow-ups via email or SMS. AI can aid with messaging, and predefined governance regulates automation.
Step 7: Move Qualified Leads Into the Mortgage Pipeline
Qualified prospects move through stages such as contacted, appointment scheduled, application started and application submitted. This helps the loan teams see progress through the mortgage process pipeline.
Step 8: Connect the CRM With the LOS
CRM and LOS integration allows relevant lead and application data to move between systems. It will help prevent duplication of entries and give visibility of the process from inquiry to loan.
Step 9: Track Conversion and Revenue
Data Analytics helps measure the lead sources and sales activities that result in the generation of applications and closed loans. The metrics that can be measured include conversion rate, cost of lead, and cost of loan funded.
Step 10: Use AI Insights to Improve Future Campaigns
Closed-loan outcomes can be used to check which lead sources generate better results in downstream processes. These insights can be used to plan future marketing campaigns.
Key Features of an AI Mortgage Lead Management System
Omnichannel Lead Capture
Capture mortgage inquiries through websites, ad campaigns, emails, SMS, partner referrals, and other third-party platforms in one platform. Lead source and campaign information can remain linked to the lead record to ensure accurate attribution.
For instance, a mortgage broker getting leads from Google ads, real estate referrals and a mortgage marketplace can consolidate all three sources in one CRM system as opposed to maintaining separate lead lists.
AI-Powered Lead Qualification
AI can help in organizing the information obtained from forms and interactions such as the loan purpose, amount of loan required, property type, and the timeframe for purchasing a house.
For example, a lead mentioning a home purchase within the next 30 days can be flagged for prompt review and on the other hand, a prospect still researching mortgage options can enter a longer nurture workflow.
Smart Lead Scoring
Using AI technology, leads can be scored based on certain criteria such as engagement, response history, lead source, and mortgage intent. The loan officer can then prioritize leads that have more engagement.
Example: An individual who inquires about a mortgage and visits the lender’s website multiple times can score higher on engagement compared to a less engaged lead.
Intelligent Lead Routing
Automatically assign leads to the appropriate loan officer based on criteria such as location, loan type, availability, and license configuration settings. This minimizes manual routing and ensures that new leads do not go unassigned.
Example: A multi-state mortgage brokerage business can route a qualified California lead to an available loan officer who can handle that state.
AI Mortgage Chatbot
An AI chatbot can answer common mortgage-related queries, and preliminary customer information can be gathered prior to handing over the interaction to a loan officer.
Example: Someone visiting a website who wants to know how to apply for a mortgage can get an instant answer and share their contact details with the loan officer.
Automated Lead Follow-Up
Automate approved email and SMS communications based on the following: newly generated leads, missed calls or any other trigger events.
Example: A new mortgage inquiry can receive an immediate acknowledgment followed by a scheduled reminder if the prospect does not respond.
AI Voice Assistant
AI voice assistants can help start conversations with leads, gather initial information and arrange appointments. Information about conversations can then be included in the CRM for the assigned loan officer.
Example: Better's Betsy is an example of AI voice technology being used in the mortgage industry to handle borrower conversations and assist with loan-related interactions.
Lead Management Dashboard
A centralized dashboard gives mortgage teams visibility into new leads and conversion activity. Managers can use the dashboard to identify pipeline gaps and monitor team performance.
Example: A branch manager can quickly identify leads that have not received a follow-up instead of checking individual loan officer records.
AI Conversation Summaries
AI can summarize permitted call and message data and highlight relevant information for the loan officer. This reduces the need to manually review long conversation histories.
Example: After a borrower call, the system can generate a summary containing the stated loan purpose, follow-up requirements and agreed next action for review before saving it to the CRM.
CRM and LOS Integration
Connect the lead management system with existing CRM and loan origination systems. This allows relevant lead and application information to move between platforms without repeated manual entry.
Example: A qualified prospect can remain in the CRM during the sales stage and have relevant application information synchronized with the LOS once the borrower starts the loan process.
Lead Nurturing and Reactivation
Keep eligible prospects engaged through longer-term workflows and identify older leads that show renewed interest. The system can surface these records for review before outreach begins.
Example: A previous refinance inquiry that returns to the lender's website can be flagged for the loan team instead of remaining buried in an inactive lead database.
Marketing and Lead Source Analytics
Track where mortgage leads originate and connect those sources with downstream outcomes such as qualified leads and funded loans.
Example: A lender can compare leads from paid search against realtor referrals to see which source generates more applications and funded loans rather than judging campaigns only by lead volume.
Role-Based Access and Audit Logs
Control access to mortgage lead data based on user roles and maintain records of important system activity. This helps businesses manage sensitive borrower information and investigate changes when required.
Example: A loan officer may access assigned leads while a sales manager can view team-level activity and an administrator manages system permissions.
AI Technologies Used in Mortgage Lead Management Software
Different AI technologies manage different parts of mortgage lead management. Some work on borrower conversations and others analyze lead behavior. Let's discuss the main technologies used in AI mortgage lead management system development.
Large Language Models
Large language models aid the system in understanding and generating natural language. They can power an AI loan officer assistant that supports daily communication and lead management tasks.
- Draft borrower follow-up messages
- Summarize conversations
- Answer common questions using approved information
- Generate email and SMS content
- Assist loan officers with lead research
Natural Language Processing
Natural language processing helps conversational AI for mortgages understand information from borrower messages, emails, chats and forms.
- Identify mortgage intent
- Extract loan purpose and buying timeline
- Understand borrower questions
- Classify conversations
- Detect important information from messages
Predictive Analytics
Predictive analytics uses historical and current lead data to identify patterns that can help mortgage teams prioritize their pipeline.
- Identify high-engagement leads
- Predict potential conversion signals
- Forecast lead activity
- Compare lead source performance
- Support predictive mortgage analytics
Machine Learning
Machine learning allows mortgage AI systems to improve their predictions by learning from historical lead and conversion data.
- Improve lead scoring
- Identify patterns in borrower behavior
- Refine lead routing
- Detect changes in engagement
- Improve campaign targeting
Recommendation Engines
Recommendation engines analyze lead activity and suggest the next action for the loan officer.
- Recommend when to follow up
- Suggest the next sales action
- Identify leads that need attention
- Recommend relevant content
- Prioritize daily tasks
Speech-to-Text and Voice AI
Speech-to-text changes important calls into searchable text while voice AI can support defined borrower interactions.
- Transcribe mortgage calls
- Summarize conversations
- Extract follow-up tasks
- Schedule appointments
- Support after-hours lead engagement
Retrieval-Augmented Generation for Mortgage Knowledge
RAG connects generative AI with approved business information. Instead of relying only on its training data, the system retrieves relevant content from a controlled knowledge base before generating a response.
- Retrieve approved mortgage information
- Support generative AI mortgage applications
- Answer questions using internal content
- Ground chatbot responses in approved sources
- Help loan officers find relevant information
AI Agents and Workflow Automation
AI agents can manage defined tasks across mortgage automation software. They can monitor events, trigger workflows and pass tasks to employees when human action is required.
- Monitor new lead activity
- Trigger approved follow-up workflows
- Update CRM records
- Schedule appointments
- Move leads between workflow stages
- Escalate conversations to loan officers
Human-in-the-Loop AI
Human-in-the-loop design keeps loan officers involved when AI recommendations or generated content require review.
- Review AI-generated messages
- Approve sensitive communications
- Check AI recommendations
- Handle complex borrower questions
- Override automated actions
- Maintain review and audit records
Develop a Mortgage AI Platform That Fits Your Workflow
Move beyond generic CRM features with custom AI workflows designed around your lead sources, sales stages, integrations, and compliance requirements.
AI Mortgage Lead Management Integrations
The AI mortgage lead management system should integrate with the current systems that mortgage businesses are leveraging. These integrations enable lead data, borrower activity and workflow changes to flow between platforms without having to manually enter it again.
Mortgage CRM Integration
CRM integration keeps lead profiles and follow-up activity synchronized with platforms like Salesforce and Microsoft Dynamics 365. The AI system can read CRM data and send updated lead information back after scoring or routing.
Loan Origination System Integration
LOS integration links the lead management system to systems that are utilized once the borrower enters the loan application process. APIs or middleware can be used to send relevant borrower and lead data to platform tools like Encompass, which minimizes data entry between sales and lending processes.
Website and Landing-Page Integration
Website integration captures inquiries from mortgage calculators, contact forms, prequalification pages and campaign landing pages. Every submission can be sent directly to the lead management platform via Webhooks or REST API with source, campaign and consent information.
Email and SMS Integration
Email and SMS integration enable you to communicate at every stage of the lead journey automatically. Twilio SendGrid, Twilio SMS, or any other predetermined service provider can be integrated with the platform for managing delivery, replies, opt-outs and communication history.
Calendar Integration
Calendar integration allows prospects to schedule calls or consultations directly with available loan officers. Connections with Google Calendar or Microsoft Outlook can synchronize appointment availability and rescheduling events.
Analytics Integration
Analytics integrations combine lead activity with business performance data. Tools such as Google Analytics 4, Power BI or Tableau can help teams gain insights into the performance of their leads, conversions, response rates, and even revenue metrics at every stage of the mortgage pipeline.
Identity and Authentication Integration
Identity integrations manage who has access to borrower/lead information. The platform can be integrated with existing identity providers using OAuth 2.0, OpenID Connect, SSO and multi-factor authentication, and role-based access control can limit access to data and functions for the user.
Mortgage AI Compliance: What Developers Must Consider
Mortgage AI software processes sensitive data of borrowers and may affect how the leads will be communicated, sorted, or routed. Depending on the intended purpose of the product, its workflow, organization, and specific use case and jurisdiction, there might be different compliance issues to consider. Qualified mortgage compliance and legal experts need to be involved to determine these compliance requirements.
ECOA and Regulation B Considerations
The Equal Credit Opportunity Act and Regulation B can apply when software is used in activities covered by their requirements. You need to determine whether AI functionality impacts any credit processes and to ensure proper control mechanisms and documentation are in place. Current Regulation B compliance needs to be verified against the latest rules of the CFPB, not old checklists.
Fair Lending and AI Decision-Making
AI models used for lead scoring, prioritization, or recommendations should be tested for potentially discriminatory outcomes. Teams should document input variables, performance of the algorithm, and human review where there may be impact on borrower access to credit.
FCRA Considerations
If consumer report information is used within a mortgage workflow, you need to account for applicable Fair Credit Reporting Act requirements. Data access, permissible use, and related processes should be defined before integrating credit-related information into the platform.
RESPA Considerations
Mortgage lead systems should be reviewed for workflows involving referrals, marketing agreements, and settlement services. Any automated referral and partner management tools should be developed in compliance with RESPA requirements.
HMDA Data Considerations
HMDA requires covered institutions to collect and submit certain mortgage lending data. It should be determined whether there is HMDA data in the process and if the platform collects, stores, and reports it in the right way.
TCPA and Automated Communications
Automated calls and text messages can create compliance requirements under the Telephone Consumer Protection Act. Consent management, calling rules, opt-out capabilities, and communication records should be incorporated into the automated outreach process.
How to Build an AI Mortgage Lead Management System
To develop an AI mortgage lead management system requires adding Artificial Intelligence to a current CRM. The process should connect goals, AI models, and more.
Step 1: Define Goals and Lead Sources
Begin by finding what the mortgage lead management solution needs to improve. This could include faster lead response or improved lead reactivation.
Map where leads currently come from, such as:
- Website forms
- Paid advertising
- Realtor referrals
- Mortgage marketplaces
- Social media
- Email and phone campaigns
Step 2: Map the Mortgage Lead Workflow
Document how a lead progresses from initial interest all the way to application and closing. List the phases, who owns what, and the actions needed.
This enables you to identify which phase in the workflow can be helped by AI without interfering with existing sales processes. AI may be used to qualify leads, after which loan officers may engage the borrowers for a more comprehensive discussion.
Step 3: Define AI Use Cases and Data Requirements
Select the AI capabilities that support business goals. Popular use cases include lead scoring, qualifying, conversations, recommendations, and reactivating leads.
Afterwards, define the necessary data points for each use case. These data points may include lead source, interaction details, conversations, and loan preferences.
Step 4: Design the Platform and Lead Data Model
After this, create the technical foundation. The architecture should also define how the platform connects with the CRM and other third-party systems. API design and event handling should be planned before AI software development begins.
Step 5: Develop the Platform
The next step is to build the AI mortgage lead management platform. Start with the core lead management features, then integrate AI capabilities around them.
Key development areas include:
- Lead capture and management
- Lead scoring and qualification
- Lead routing
- AI chatbot or assistant
- Email and SMS automation
- Conversation summaries
- Next-best-action recommendations
- Lead nurturing workflows
AI outputs should remain subject to defined business rules and human review where appropriate.
Step 6: Integrate Mortgage Systems
Connect the platform with the systems already used by the mortgage business. This may include CRM platforms, LOS platforms, email and SMS providers, calendars, telephony systems and marketing tools.
Use APIs and webhooks to synchronize relevant events while avoiding unnecessary duplication of sensitive borrower data.
Step 7: Add Security, Compliance and Testing
Security and compliance should be built into the system rather than added after AI mortgage lead management system development.
Test areas can include:
- Role-based access
- Encryption
- Authentication
- Consent and opt-out handling
- Audit logs
- AI output accuracy
- Lead routing rules
- Integration failures
- Data access controls
Compliance requirements should be reviewed for the specific institution and jurisdiction by qualified professionals.
Step 8: Launch, Measure and Improve
Start with an MVP focused on the best lead management workflows. After launch, monitor performance using metrics like response time, cost per qualified lead and funded-loan conversion.
Use these results to refine scoring models, automation rules and AI workflows over time. The system should improve based on real business data rather than adding AI features without a measurable purpose.
Cost to Develop an AI Mortgage Lead Management System
The AI mortgage lead management system development cost can range from $25,000 to $200,000+. It depends on various factors like integrations and complexity.
| Complexity level | Estimated cost | Development timeline | Key features included |
| MVP | $25,000 – $50,000 | 2 – 3 months | Basic CRM pipeline, rule-based lead routing, AI-assisted email and SMS drafting, standard web form lead capture |
| Mid-level | $50,000 – $120,000 | 4 – 6 months | Omnichannel AI chatbots, AI voice and text qualification, CRM and LOS integrations, lead scoring, analytics and workflow automation |
| Advanced | $120,000 – $200,000+ | 6 – 12+ months | Predictive lead scoring, voice AI, advanced analytics, multiple LOS and third-party integrations, advanced security and custom AI workflows |
These figures provide a development planning range rather than a fixed quote. The final budget depends on the product scope, integrations, user volume, AI architecture and compliance requirements.
Factors That Affect AI Mortgage CRM Development Cost
Several factors can increase or reduce the development effort:
- Number of integrations: Integration with CRMs, LOS, marketing tools, telephony systems and others would require more API development.
- AI specifics: Generative AI and basic automation require less development effort than predictive analytics, voice AI and custom AI algorithms.
- Number of users: Larger user bases might require more complex roles and permissions.
- Communication channels: Web chat, email, SMS and voice require separate workflows and service integrations.
- Security needs: Encryption, MFA, RBAC and audit logging will increase development scope.
- Compliance requirements: Mortgage-specific compliance requirements may involve specific workflows.
- Dashboards: Custom sales, lead and performance dashboards would require extra UI and data processing.
- Data migration: Historical lead and communication data migration from existing systems might take significant time.
- Mobile applications: Native or cross-platform mobile apps would increase the scope of work.
- Cloud infrastructure: AI services, database, storage and monitoring require cloud infrastructure.
- Third-party API: AI models, SMS, voice and data providers might bill separately according to usage.
Build vs Buy: Should You Develop a Custom AI Mortgage CRM?
The choice between buying an existing CRM and creating a custom AI mortgage CRM is determined by the business processes, integration requirements, budget, and future requirements.
When Buying Existing Software Makes Sense
Existing software could be beneficial if the features of the existing CRM and AI workflows fit the business requirements.
Example: A small brokerage company that requires only lead generation, automation, and basic reports may choose an existing CRM instead of creating a new one.
When Custom Development Makes Sense
Custom software development becomes very useful when the business needs workflows, integrations or AI capabilities that current platforms cannot support without customization.
Example: A multi-state mortgage company may need custom lead routing connected to its CRM, LOS, telephony system and internal compliance workflows.
Custom AI Mortgage CRM vs Off-the-Shelf CRM
| Factor | Off-the-shelf | Custom |
| Initial cost | Lower | Higher |
| Customization | Limited | High |
| Ownership | Vendor | Business |
| Integrations | Available options | Custom |
| AI workflows | Prebuilt | Tailored |
| Scalability | Vendor-dependent | Controlled |
Total Cost of Ownership
Compare more than the initial development or subscription cost. Consider licensing, customization, API usage, maintenance, AI services, infrastructure and future upgrades.
Data Ownership
Review where lead and borrower data is stored, how it can be exported and what access the vendor has. Custom platforms can provide greater control over data architecture and storage policies.
Custom Workflow Flexibility
Custom software allows businesses to design lead stages, routing rules, AI workflows and dashboards around their existing processes instead of adapting operations to a fixed CRM structure.
Integration Requirements
Existing CRM products may offer standard integrations, while custom development allows deeper connections with systems such as Encompass, MeridianLink, telephony platforms and internal applications.
Compliance and Governance Requirements
Businesses with specific security, data governance or compliance workflows may need greater control over system behavior, access permissions, audit trails and AI oversight.
Real-World AI Mortgage Lead Management Use Cases
AI mortgage lead management can support different stages of borrower acquisition. Let's look at a few use cases of how AI can be utilized by lenders and mortgage companies to capture leads and assist loan officers in working on those higher-value opportunities.
Purchase Mortgage Lead Automation
Property search, mortgage calculators, website forms and advertising campaigns are all ways of acquiring purchase leads. AI can analyze these interactions and uncover prospects with increased purchase intent.
For instance, a borrower researches mortgage rates, runs a monthly payment worksheet, and completes a prequalification within the same week.
Refinance Lead Follow-Up
Refinance prospects may take time before deciding to move forward. AI can track engagement and tailor follow-up in response to the borrower's response to previous outreach.
Example: A previous borrower opens several refinance messages but does not respond. When the system detects renewed interest after a few more interactions with the lender's rate content, it sends the lead back to the loan officer rather than placing it in a dormant segment. Such a workflow can help mortgage teams remain connected with a prospect while in a longer decision-making process.
First-Time Homebuyer Lead Nurturing
First-time buyers often need information before they are ready to apply. An AI system can provide approved educational content while tracking questions and engagement.
Example: A new prospect asks about down payments and qualification requirements through the mortgage website. The AI assistant shows the user verified data, logs the interaction and notifies a loan officer if the user has a question that needs individualized guidance. Built around first-time home buyers, who made up 32% of home buyers in the 2024 National Association of Realtors Profile of Home Buyers and Sellers, workflows must cater to these buyers who may require more guidance.
Realtor Referral Lead Management
The response time of referral leads is crucial, and the referral source should be accurately attributed. A mortgage lead management system can integrate the referral source to the borrower record and monitor the lead in the pipeline.
Example: A realtor refers a homebuyer who is actively seeking financing. The system logs the referral, evaluates the routing rules, and assigns the prospect to a qualified loan officer. The referral partner and internal team can then track the lead’s status throughout the defined process.
Mortgage Marketplace Lead Routing
Mortgage companies can attract prospects who have various loan needs, areas and qualification requirements. These leads can be distributed with the help of AI-assisted routing, following the predefined business rules.
Example: There are a few mortgage inquiries sent at the same time to a marketplace. One is considering buying a home and the other is considering refinancing. The system detects the purpose of the loan, its location and other necessary details before passing each lead to the right team.
Multi-State Mortgage Brokerage Operation
A multi-state brokerage may have to take into consideration where the lead came from, licensing, the type of loan, and loan officer availability when deciding on where to assign leads. These rules can be added to an automated routing workflow.
Example: A borrower submits an inquiry from one state for a specific mortgage product. The system checks the configured routing criteria and sends the lead only to an eligible loan officer who can handle that type of inquiry in the borrower's location. If no suitable officer is available, the workflow can trigger an escalation for manual assignment.
Future of AI Mortgage Lead Management
AI mortgage lead management will likely evolve from simple automation to systems capable of interpreting borrower intent and aiding loan officers and streamlining more intricate workflows.
Agentic AI for Mortgage Sales Workflows
Agentic AI can perform multiple tasks like tracking new leads, drafting follow-up emails, entering the leads into the system, and reengaging the leads for further action when necessary.
AI-Powered Sales Coaching
AI can analyze conversations, response patterns and pipeline activity to give loan officers practical coaching suggestions. This could include follow-up timing and conversation gaps and suggested next steps.
Predictive Borrower Intent
There is potential for future systems to use behavioral signals to determine when a borrower is becoming more likely to engage or apply. This can assist companies prioritize leads on intent, not just lead volume.
Voice AI for Mortgage Lead Engagement
Voice AI is expected to be more beneficial for screening leads, scheduling appointments and follow-up calls. It will help loan officers handle complex or sensitive conversations.
Automated Referral Management
AI can be used to monitor referral activity and pinpoint follow-up opportunities to suggest when referral partners or prospects should be contacted.
AI-Powered Pipeline Forecasting
AI may integrate historical conversion information with pipeline data to offer more dynamic predictions for applications, funded loans and demand for leads.
More Explainable and Auditable AI
Mortgage businesses will increasingly focus on understanding the rationale for an AI system's score, recommendation or routing decision. Clear reasoning records and audit trails can be used to help with internal review.
Why Choose Suffescom for AI Mortgage Lead Management Development
Mortgage lead management needs more than adding AI to an existing CRM. The system needs to fit the lender’s workflow and also needs to keep borrower data secure and give loan officers useful information at the right time.
Mortgage Workflow Expertise
Suffescom can create workflows for mortgage lead stages (e.g., inquiry, qualification and application). AI can help with automated tasks, and loan officers can still handle the interactions with borrowers.
Practical AI Implementation
AI integrations are chosen based on the specific needs of the business. When such value is to be gained, the system can incorporate language models for conversations or predictive models for lead scoring.
Security-Focused Architecture
Security can be built into the application architecture from the beginning. Sensitive borrower data is safeguarded by access controls and encryption, and audit logs offer transparency into crucial system activity.
Scalable Development
The architecture can accommodate growth of the mortgage business as volumes increase. New workflows or communication channels can be added without rebuilding the entire application.
Post-Launch Support
Mortgage workflows change as business requirements evolve. Suffescom provides ongoing support for system improvements and integration maintenance after deployment.
Conclusion
AI mortgage lead management can enable lenders to respond more quickly while providing loan officers with improved visibility of borrower activity. The value comes from connecting lead capture with qualification, follow-up and pipeline management in one workflow.
A custom system can facilitate AI powered scoring and personalized engagement while maintaining vital choices within human control. The right architecture can also integrate CRM and LOS data without impacting current mortgage processes.
For businesses planning to develop an AI mortgage lead management system, the mortgage software development scope should be based on lead volume and integration requirements. A focused MVP can establish the core workflow before advanced AI capabilities are introduced as the platform grows.
Discuss Your AI Mortgage Lead Management Project
Share your lead volume, existing systems, integrations, and automation goals to plan the right architecture and development scope.
FAQs
1. What is an AI mortgage lead management system?
An AI mortgage lead management system is software that helps lenders capture, qualify, score and manage mortgage prospects. AI can analyze lead activity and assist with follow-ups while loan officers handle important borrower interactions.
2. How does AI improve mortgage lead management?
AI can reduce manual lead management work and help teams respond to prospects faster. It can identify engagement signals and recommend which leads need attention.
3. How much does it cost to develop an AI mortgage lead management system?
AI mortgage software development can cost around $25,000 to $200,000+ depending on the system scope. Integrations and advanced AI capabilities can significantly affect the final budget.
4. How long does it take to build an AI mortgage CRM?
A basic MVP can take around 2 to 3 months. A more advanced system with multiple integrations and AI capabilities may require 6 to 12+ months.
5. What features should an AI mortgage CRM have?
Important features can include:
- AI lead scoring
- Lead routing
- Automated follow-up
- AI chatbot
- Voice AI
- Lead analytics
- CRM and LOS integration
- Conversation summaries
- Lead reactivation
- Role-based access
6. Can AI qualify mortgage leads automatically?
Yes. Artificial Intelligence can collect information and evaluate predefined qualification signals. High-impact lending decisions should remain subject to appropriate business rules and human review.
7. Can an AI mortgage CRM integrate with an LOS?
Yes. APIs and middleware can connect an AI mortgage CRM with an LOS. Lead and application information can then move between systems based on the configured workflow.
8. Can AI automate mortgage lead follow-up?
Yes. AI can trigger email, SMS or conversational follow-ups based on lead activity and workflow rules. Loan officers can take over when a conversation requires personal assistance.
9. Is AI mortgage lead management software compliant with mortgage regulations?
Compliance depends on how the software is used and the business involved. The system should be designed with applicable requirements in mind, including rules related to fair lending, borrower communications, privacy and recordkeeping.
10. How can AI mortgage software handle borrower data securely?
Security should be incorporated into the application architecture. Common controls include:
- Encryption
- Role-based access control
- Multi-factor authentication
- Audit logs
- Secure API communication
- Consent and access management
11. What is the difference between an AI mortgage CRM and a traditional CRM?
A traditional CRM primarily stores and manages customer and lead information. An AI mortgage CRM can analyze lead behavior and assist with tasks such as scoring, follow-up and next-action recommendations.
12. Should mortgage companies build or buy an AI CRM?
Buying can work when standard CRM features meet the business requirements. Custom development is more suitable when a mortgage company needs specialized workflows, integrations or AI capabilities.
13. Can an AI system route to licensed loan officers?
Yes. Lead routing can use configured criteria such as location, loan type and officer availability. Licensing-related rules should be validated against the lender's compliance requirements before automated assignment.
14. Can AI predict which mortgage leads are most likely to convert?
AI can estimate conversion likelihood using historical outcomes and available behavioral signals. The resulting score should be treated as a decision-support signal rather than a guaranteed prediction.
15. How can mortgage companies calculate AI CRM ROI?
Companies can compare implementation and operating costs against measurable business outcomes such as:
- Higher lead-to-application rates
- Faster response times
- Lower cost per qualified lead
- More funded loans
- Reduced manual work
16. How do I choose an AI mortgage software development company?
Look for a mortgage software development company with experience in AI systems and mortgage workflows. Review its integration capabilities and security approach. Ask how it handles testing, human oversight and post-launch support before starting the project.