+971-8000321216


Key Takeaways:
- Traditional debt collection methods are becoming harder to scale efficiently. Collection teams need better ways to prioritize overdue accounts, predict payment behavior, reduce repetitive work, and manage borrower communication. AI-powered debt collection can help automate these workflows while keeping decisions within defined business rules and compliance requirements.
- The U.S. debt market highlights the scale of the challenge. In Q2 2026, U.S. household debt reached $18.8 trillion, with 4.7% of debt in some stage of delinquency. These figures highlight why lenders and collection agencies need effective strategies for managing overdue accounts.
- Reliable data drives better collection decisions. Accurate account balances, payment histories, delinquency records, borrower interactions, and contact restrictions provide the foundation for meaningful predictions and appropriate follow-up actions.
- Predictive AI needs a rules-based decision engine. Machine learning can estimate payment propensity and delinquency risk, while deterministic rules govern account eligibility, permitted actions, and escalation requirements.
- Scalable architecture keeps collection workflows reliable. Secure integrations, validated data pipelines, event processing, payment reconciliation, and audit trails help maintain accurate account records and traceable operations.
- Compliance and human oversight must be built in from the beginning. Privacy controls, contact restrictions, dispute handling, explainable decisions, and human review help support responsible collection practices and applicable regulatory requirements.
- Performance measurement determines whether AI delivers value. Recovery rates, cost-to-collect, promise-to-pay fulfillment, time to resolution, complaint rates, and compliance exceptions help businesses evaluate system effectiveness.
- Development costs depend on features, integrations, and complexity. Indicative estimates range from $50,000 to $100,000 for a basic MVP, $100,000 to $250,000 for an advanced AI platform, and $250,000 to $500,000 or more for an enterprise solution. These are planning estimates, not fixed market prices.
- The right development approach can control long-term costs. Businesses should compare custom development, existing platforms, and hybrid solutions based on integration needs, data readiness, security, scalability, customization, and total cost of ownership.
As overdue account volumes grow, fragmented records, repeated borrower inquiries, and manual prioritization make debt recovery harder to manage. Scale matters; US household debt was $18.8 trillion in Q2 2026, with 4.7% of outstanding debts at various stages of delinquency, as per the Federal Reserve Bank of New York's latest report.
With AI-powered debt collection tools, companies are able to manage their debts more efficiently by prioritizing accounts, predicting payments, personalizing communications, and automating processes for handling complicated issues, among others. But creating an efficient system is not just about having a chatbot. Reliable data pipeline requirements include prediction algorithms, integration solutions for security purposes, and decision engine functionality, as well as regulatory control measures.
Here, we'll explore the key characteristics and design of an organization’s software systems to implement artificial intelligence technology for developing applications through integration processes while also considering legal issues related to cost-effectiveness.
What Is an AI-Powered Debt Collection?
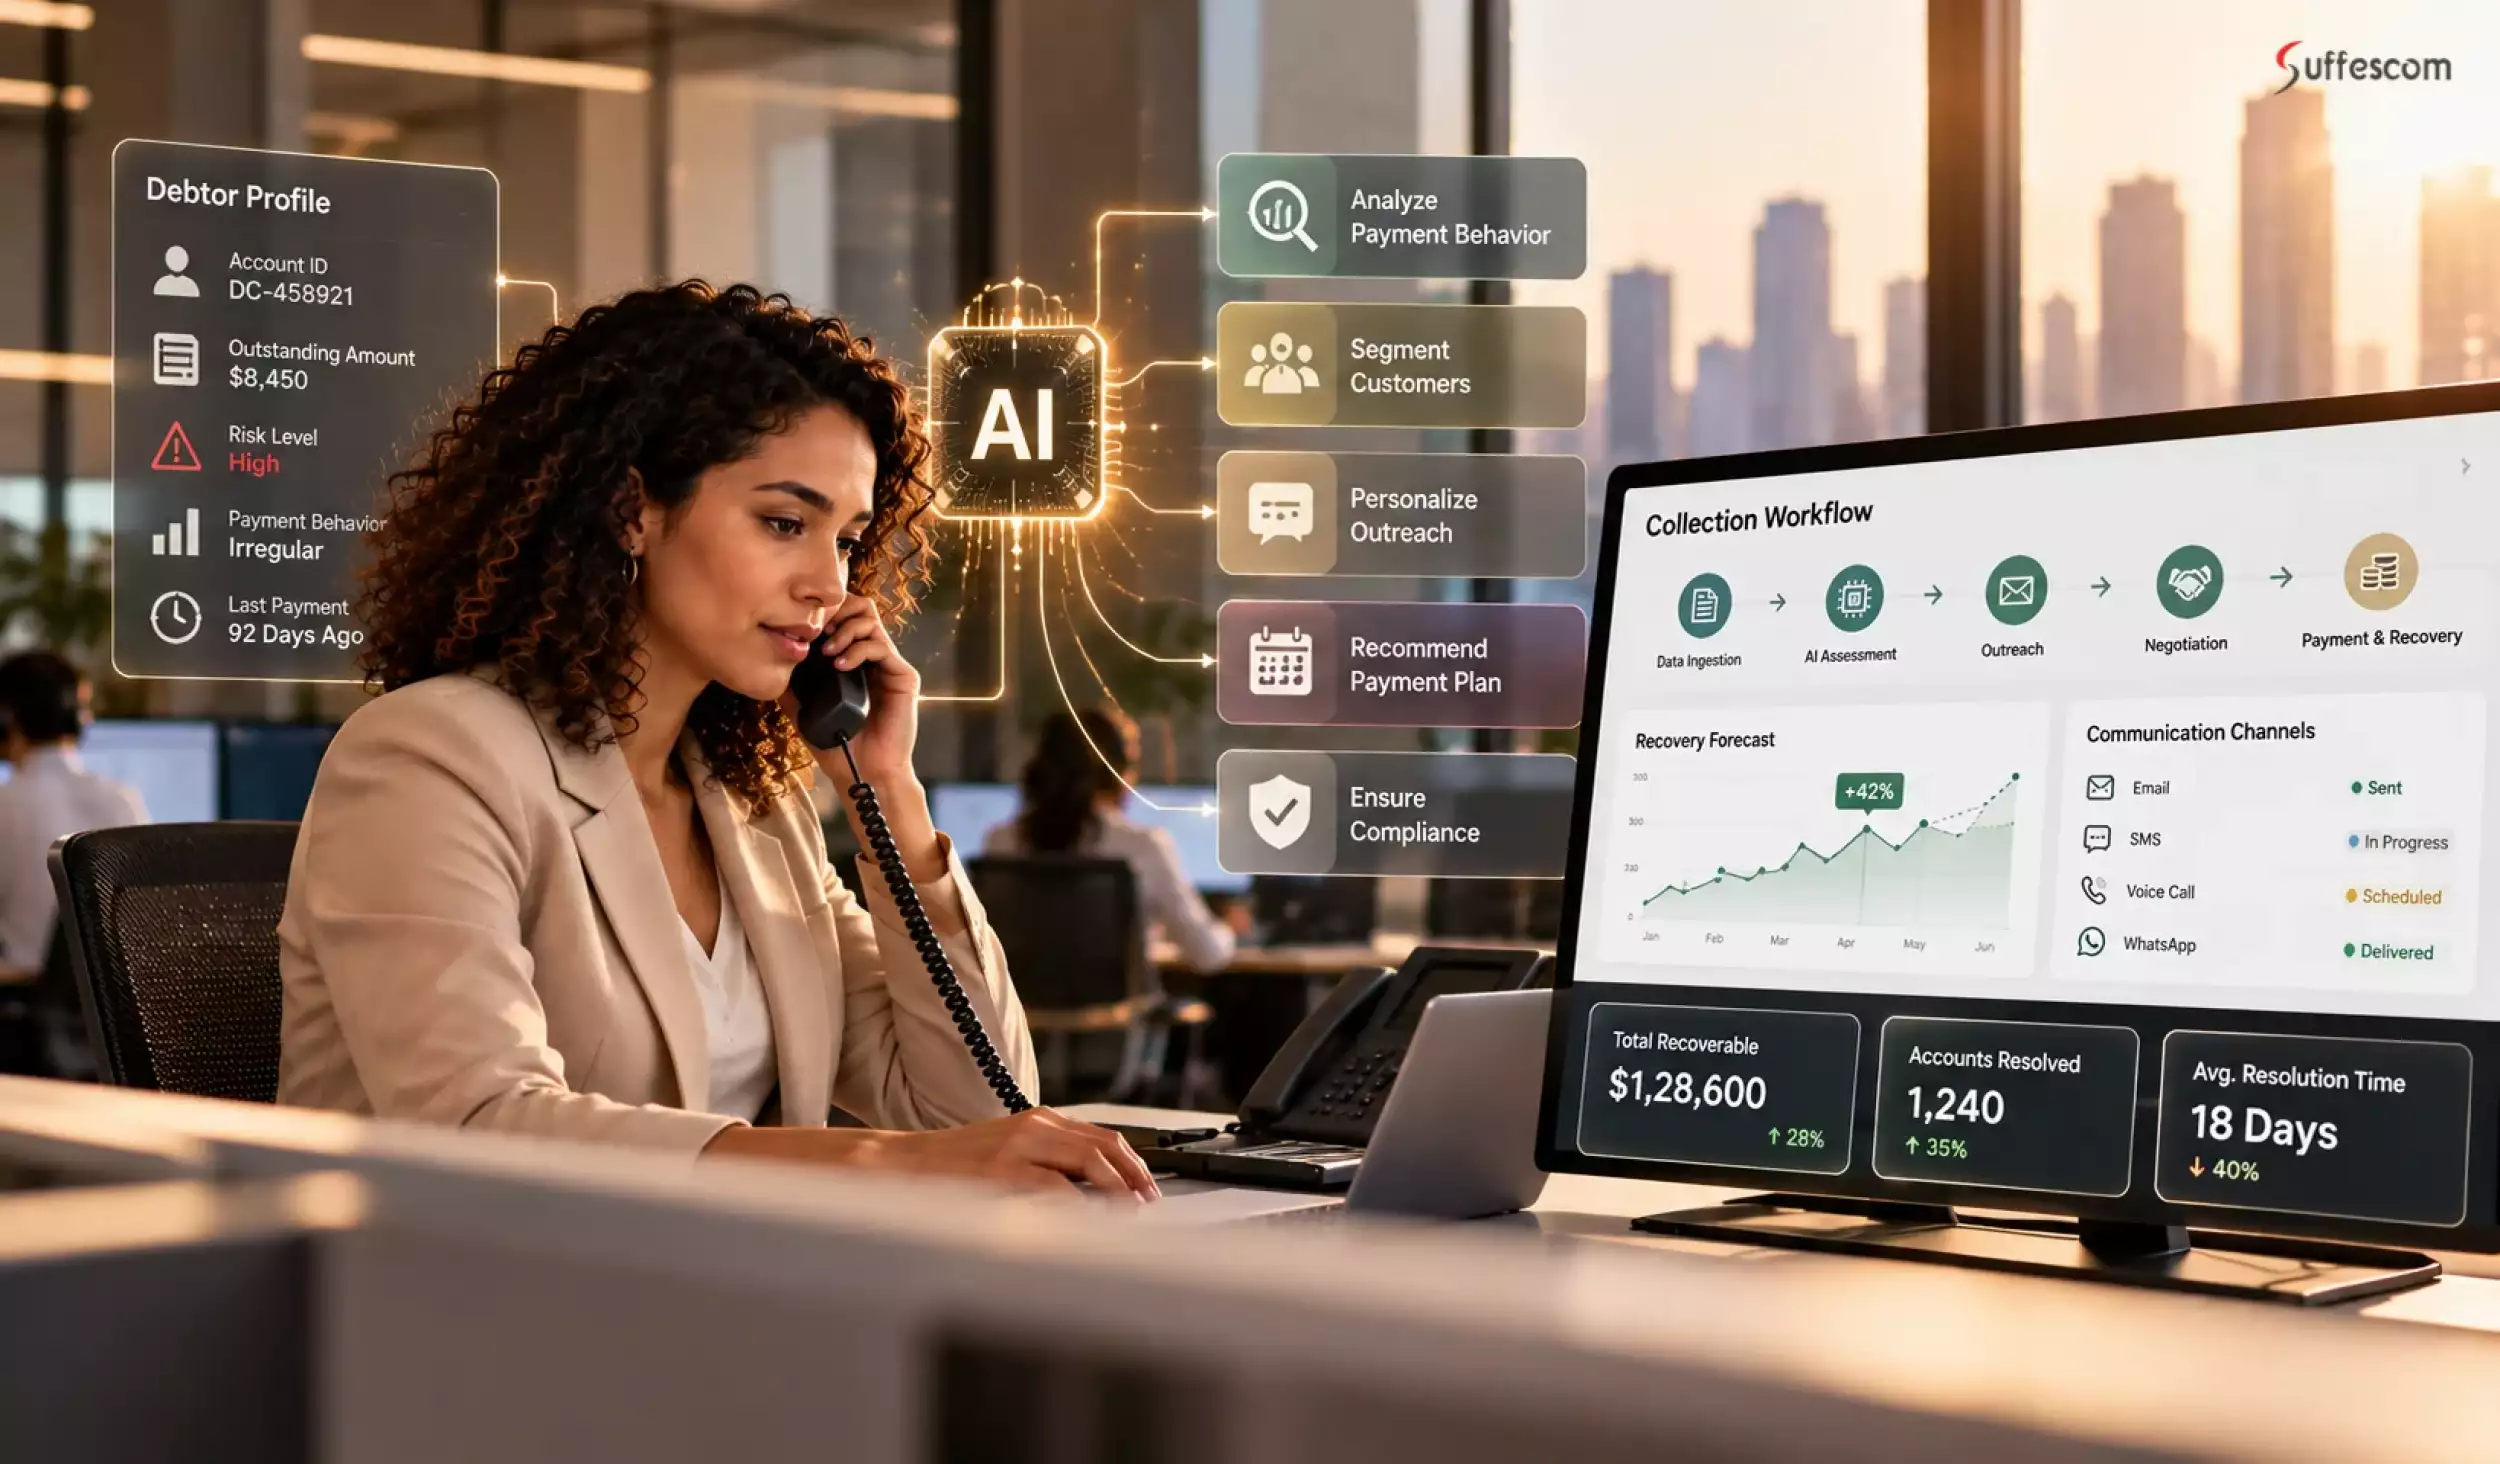
AI-powered debt collection is an application of artificial intelligence for managing unpaid bills by using predictive analytics, natural language processing, and workflow automation techniques. This tool reviews customers' payment histories and account records to identify delinquency patterns, recommends ways to contact them about their debts, and tracks how well they pay back loans over time.
Conventional approaches rely solely on static data sets for making suggestions about product selection. However, they do not address issues like conflict resolution or handling difficult situations by humans themselves.
How AI Changes the Debt Collection Lifecycle
Traditionally, collection management is based on a set schedule and manual follow-up procedures. AI introduces data-driven decision-making at each stage.
- Assessment of accounts consolidates payment records and transactional information.
- Payment priority ranking for predicting the probability of payment delay and default chances.
- Customer engagement strategy for recommending appropriate contact methods and messaging style.
- Tracking of payments and promises-to-pay tracker.
- Optimization of strategy through measurement results for improvement purposes.
A recommendation should be made within the scope of permission for communication purposes under law.
AI-Powered Debt Collection vs. Traditional Automation
Rule-based automation executes predefined conditions, while AI models identify patterns and estimate likely outcomes. Generative AI interprets language and drafts responses, whereas agentic workflows use authorized tools to complete specific tasks.
| Approach | Primary function | Example |
| Manual collections | Human-led decisions | Collectors review accounts individually. |
| Rule-based automation | Executes predefined rules | Sends reminders when payments become overdue. |
| Predictive AI | Estimates likely outcomes | Prioritizes accounts by payment likelihood. |
| Generative AI | Understands and generates language | Drafts responses to payment queries. |
| Agentic workflows | Completes bounded tasks using approved tools | Retrieves account status and logs a permitted follow-up. |
A well-designed AI debt collection platform combines these capabilities with validation, access controls, audit trails, and human oversight. Applicable to US consumers' collection laws are the FDCPA and Regulation F.
Who Needs an AI Debt Collection Platform?
AI-powered debt collection software helps businesses manage their high volume of outstanding accounts such as these.
- Banking institutions and credit card companies should prioritize outstanding debts and develop collection plans for them.
- Automated follow-up for fintech lenders and consumer credit agencies to evaluate payment behavior.
- Client management agency for managing clients' collections and improving collectors' efficiency.
- Pay later buy now service for tracking unpaid bills and identifying payment risk.
- B2B accounts receivable teams to pay off overdue bills and forecast payment delays.
Collection size, current infrastructure requirements, and regulations determine which platform is best suited for us. There are disputes, hardship requests, and sensitive issues that need to be reviewed by humans instead of being solely based on machine-based decision-making processes.
Why Are Businesses Adopting AI in Debt Collection?
With increasing amounts of overdue accounts on file, it becomes more difficult for us to collect them manually. With AI development in debt collection, companies can manage larger amounts of work better, decide which ones to recover effectively, and provide a uniform customer experience by eliminating human involvement altogether.
Increasing Account Volumes Without Proportional Staffing
More reminders about growing the portfolio lead to payment inquiries, account review requests, and follow-up calls. Adding more people to do all of them would be expensive. Automation of workflows allows for efficient management by employees so they can concentrate their time on more complicated issues. The effect may be measured by the number of accounts managed by each collector, time spent on a task manually done, and expenses incurred for handling an account.
Improving Account Prioritization and Recovery Decisions
Not every overdue bill is equal to others in terms of probability of payment, amount due, and service needs. A predictive model may be used to rank an account based on its payment history and level of delinquency. It allows for better allocation of collectors' resources rather than treating all accounts equally. Contact success rate and payment guarantee level of satisfaction among customers for each category are useful measures to evaluate them.
Creating More Consistent Borrower Experiences
Repeated messages, inappropriate communication methods of contacts, and slow response times may be frustrating for borrowers. An integrated system would be able to accommodate a customer’s preferred communication channels while providing transparent billing details along with easy-to-use online services for customers’ convenience. Also, it will be able to send out complaints and difficulties faster from an employee. Companies may measure them by response time, complaint rate, self-service completion percentage, and success in resolving issues.
Key Benefits of AI-Powered Debt Collection Software
The AI-based debt recovery system is an application of data analysis techniques for better collections process management through automated processes and communication channels. The actual result depends upon data quality, portfolio characteristics, implementation, and regulatory control. Therefore, each advantage must be measured from an objective standard of reference.
Improved Collection Productivity
Summarization of accounts by automation; priority task management system for work queue processing; automated process to handle regular follow-ups. The collector spends less time solving complicated problems rather than searching through separate databases. Accounts managed by collectors, time spent on cases, and man-hours for measuring productivity improvements are tracked.
Better Recovery Prioritization
The payment propensity prediction model is used for predicting payments and estimating their recoveries, which helps in organizing the collections queue management system. The manager may use this information along with account statuses of customers, collectors' capacities to collect them, and any other relevant restrictions for prioritizing matters at hand. Recovery rate can be measured as a percentage of priority groups fulfilled for promises made on payment terms and collectors' time spent per category.
Lower Cost-to-Collect
Automation of processes and online payments will help eliminate manual tasks like repeated processing and redundant communication between departments, as well as paperwork that is no longer needed. These features can reduce the average cost of managing an account if there are no extra mistakes made by automation or escalation issues. Cost of an account, rate for a successful recovery by us, hours worked to do it.
Consistent Omnichannel Engagement
Unified interaction histories help to coordinate allowed communications between different types of media, like emails, text messages, calls over telephone lines, or through a website portal for customers' information needs. It eliminates duplicate contact attempts while providing information to buyers prior to answering their questions. Contact measurement rates of effectiveness, response rates per channel, duplication incident count, and complaint statistics under enforcement regulations for communications policies.
Better Portfolio Visibility
Live reports of accounts are useful for monitoring delinquencies by management to track collections results on a daily basis. Segmentation of a portfolio may help identify areas for improvement and resource allocation needs to be addressed. Recovery Rate, Roll Rate, Days Past Due, Promise-To-Pay Fulfillment, and Cost to Collect are useful measures of performance.
Use Cases of AI in Debt Collection
The following use cases show how businesses can improve targeting accuracy, consistency, and measurability during collections processes.
Early Delinquency Detection
Machine learning algorithms are able to detect trends related to new cases of non-payment, like frequent missed due dates or alterations in payment habits. For instance, an institution may be alerted to account delinquency rates that are rising sooner rather than later when reviewing them. Performance of teams is measured by predicting delays and changing their numbers.
Payment Propensity Scoring
The predictive model predicts how likely it is for an account to pay off or be resolved before a certain time frame ends. These ratings would help a collections company prioritize its clients' cases based on their credit history status as well as current debts owed by them. Performance of a model needs to be measured by its results rather than just prediction accuracy.
Personalized Communication and Channel Selection
AI is able to suggest appropriate communication channels based on past interactions as well as current preferences of users through data analysis. For instance, if you are a borrower who frequently answers emails, then you will get an approved email notification rather than an unwanted phone call. Eligibility for contact information availability, communication restrictions, and laws should be considered while making decisions.
Conversational AI for Routine Collections
A conversational AI system is able to provide answers for balance inquiries, payment method queries, and due date information, as well as repayment instructions. The borrower can get help from a self-service website instead of having to wait on an agent. Disputes, difficulties with the payment process, or uncertainty about customer information are handled by a suitable person.
Payment Promise Monitoring
With AI-based processes for tracking PTPs, the agreed date is compared against the payment record's time-stamped data point at any moment of need. If no payment is received from customers, it will be checked by reviewing accounts to start any relevant follow-ups, such as reviews or delivery issues. Confirmation of payments helps avoid wrong notifications.
Hardship, Dispute, and Complex-Case Routing
The AI system is able to categorize incoming emails as well as identify those requiring expert intervention. If an applicant is experiencing financial difficulties or disputes over their account balances, they should go directly to that department instead of being sent through standard reminders. The accuracy of routing, speed, and rate at which it escalates can be used to determine if a system works well.
For example: Missed payments trigger a revised credit rating. An account eligibility check is performed by a policy engine for contact restriction and communication limit purposes. When allowed to do so, it will send out an authorized notification for approval purposes; record this activity on file as well as update your profile information upon receipt of any payments or interactions.
Essential Features of AI-Powered Debt Collection Software
Reliable AI-based debt collection systems require solid infrastructure for the implementation of sophisticated artificial intelligence technologies. The account record management system, workflow control mechanism, permission setting process, and logging trail must be included as an MVP rather than being delayed for showier artificial intelligence capabilities.
Centralized Account and Portfolio
Unified Account View combines balance sheet information for debts, aged by age groups of customers' payments to accounts, as well as assignment details like customer names or addresses under each record. Provides consistency of data for investors' portfolio management while reducing time spent on switching from one system to another.
AI-Based Account Prioritization
The configurable queue combines prediction scores with a good balance of accounts, credit card approval statuses, customer loyalty program membership levels, and collection limits. It allows them to concentrate on relevant matters while preventing an AI from exceeding its limitations as per law and regulations for the approval process.
Omnichannel Communication Management
This system handles calls by phone, text messages via SMS, and emails to users' inboxes through mail services like Gmail or Outlook. Unified conversations reduce duplicate outreach; channel-level reports help us compare response rates and identify any problems with our communications.
Intelligent Workflow and Rules Engine
Workflow engines handle trigger management, condition-based transition handling, schedule execution, retry logic, approval gate processing, and exception routing. For instance, a missed payment may lead to an account review, whereas a dispute might halt regular follow-ups and refer it for further investigation by specialists.
Payment Arrangement and Promise-to-Pay
Repayment plan record date, agreement reminder confirmation failure transaction reconciled status is stored by this software application. Payment records of linked accounts are needed to manage balance sheets for collections purposes under eligibility criteria.
Collector Copilot and Case Summaries
An accounts receivable collector is responsible for summarizing accounts receivable histories, highlighting recent transactions, and drafting approvals of invoices or credit memos to be sent out to customers. The recommendations must come from an approved source of information; there needs to be a human check on important choices like those involving loans so that no unauthorized AI-generated statement reaches them.
Compliance Monitoring and Audit Trails
Compliance controls check contact eligibility, communication restrictions, required disclosures, and approval requirements before actions proceed. An audit trail must record input data points like decision-making process model rules, version history, and action logs with timestamp information for reconstruction purposes of events that occurred within a project team’s workflow cycle lifecycle stage.
Analytics and Reporting Dashboard
Dashboards track portfolio performance, recovery trends, agent productivity, channel effectiveness, delinquency movement, and operational exceptions. Drilling down to an account level helps managers analyze changes; consistency of metrics is important for making accurate comparisons between periods.
MVP vs. Advanced Capabilities
| Capability | MVP (Essential) | Advanced (Later Phase) |
| Account management | Centralized account records, balances, aging, and case status | AI-assisted account insights and portfolio segmentation |
| Integrations | Secure connections to loan servicing, CRM, and payment systems | Event-driven integrations and broader ecosystem connectivity |
| Workflow automation | Rules engine, triggers, scheduling, and exception routing | AI-driven next-best-action recommendations |
| Access control | Role-based permissions and data access restrictions | Fine-grained, context-aware access policies |
| Payment management | Payment tracking, repayment schedules, and reconciliation | Predictive payment analysis and optimized repayment workflows |
| Compliance and audit | Contact eligibility checks, audit trails, and approval gates | Advanced compliance monitoring and decision traceability |
| Account prioritization | Rule-based queues and manual prioritization | Predictive payment propensity and recovery scoring |
| Customer interactions | Approved templates and basic self-service | Conversational AI and personalized channel recommendations |
| Collector support | Account history and manual case reviews | AI-generated case summaries and collector copilots |
| Analytics | Core portfolio, recovery, and productivity reports | Predictive analytics, model monitoring, and strategy optimization |
AI Technologies Powering Modern Debt Collection Systems
Predictive analytics and natural language processing techniques are used by modern debt recovery systems for determining debts of customers' accounts. Every technology has its own function, such as predicting customer payments or analyzing loan applications, whereas business policies dictate what can be done within an organization.
Machine Learning for Payment Propensity Prediction
Machine-supervised models are used for predicting future payments based on past transaction history and previous results of similar transactions. Repayment records and delinquency statuses of past accounts are available for model training data. Predictions are useful for ranking accounts. However, they need validation by comparing them with real results and monitoring their accuracy over time.
Predictive Analytics for Delinquency and Recovery Forecasting
Predictive analytics answers some related but different problems, such as whether an account will go overdue, when payments are due, what amount can be collected from it, and how probable its resolution is. These estimates help teams plan resources and compare strategies. Every model requires an objective goal definition, temporal scope of the analysis period, and evaluation metric.
Natural Language Processing for Borrower Interactions
Intent detection by NLP systems is used to extract information from text documents like emails or chat logs for analysis purposes such as sentiment analysis, etc. For instance, this will allow us to differentiate between an invoice issue and a claim for payment disputes/hardships so that we can handle them appropriately. Thresholds of confidence levels, along with a human review system, are used to handle unclear/confidential communications.
Speech Recognition and Voice AI
The speech-to-text conversion of a call allows for intent analysis, summary generation from conversations, and feedback on product performance. Voice AI is capable of handling approved routine conversations like explaining payment options to customers up to a certain limit. Verification of identity is important for communication protocols and straightforward transfers between humans and machines.
Rule Engines and Decision Intelligence
Rules are enforced by a rule engine, which is not overridden by a prediction model. They check account eligibility, contact restrictions, approval requirements, and operational limits before an action proceeds. AI recommendation combined with an explicit rule-based system for data gathering is better at making choices that are consistent, trackable, and manageable.
Technology-to-Component Mapping
| Technology | Typical input | Output | Responsible component |
| Machine learning | Account and payment history | Payment propensity score | ML inference service |
| Predictive analytics | Historical trends and account features | Delinquency and recovery forecasts | Analytics service |
| NLP | Messages and conversation transcripts | Intent, entities, and summaries | Language processing service |
| LLMs | Borrower requests and approved knowledge | Draft responses | Conversational AI service |
| Speech recognition | Voice audio | Transcripts and detected intent | Voice AI service |
| Rules engine | Account state, policies, and model outputs | Allowed action or rejection | Decision and policy engine |
AI-Powered Debt Collection Software Architecture
Scalability of an AI-based debt collection system requires distinct components for data handling, forecasting models, decision-making processes, and implementation actions. The architecture allows for easy maintenance, integration, auditing, and scaling of this system while preventing any AI models from circumventing operational or regulatory requirements.
Overview of the Reference Architecture
The architecture is divided into eight interconnected levels.
- Source systems and ingestion: Data collection source systems and ingestions are collected through credit card companies, customer relationship management software, payment processing services, telephone networks, etc.
- Data validation and account records: Validation of data entry to ensure accuracy while maintaining consistency in accounts.
- Feature engineering and analytics: Engineering features to be used by analysts and machine learning models.
- ML training and inference: Training an ML model to make predictions on active account data.
- Decision orchestration and policy enforcement: Orchestrating decisions for decision-making purposes and enforcing policies through prediction models and creditworthiness verification processes.
- Communication and payment services: Send out dispatch-authorized messages to handle payments.
- Agent and borrower interfaces: Interface for agents and borrowers to provide collectors' workspace, dashboard, and self-service portal access.
- Security and observability: Access controls, audit decisions, system health monitoring at all levels.
Data Ingestion and Integration Layer
The API feeds this layer are scheduled batch import events and streamed from an event source. Validation of schema, duplication detection, timestamp verification, and data freshness checks are used to avoid old and incorrect accounts affecting our selection process for collecting them. Failing entries must be handled by an error-handling mechanism instead of being lost without notice.
Data Storage and Account State Management
Transactional accounts' information should be stored separately from analytics data, interaction histories of customers, and models’ parameters. Accounts will be an authoritative source of information on balance sheets and payments; analytics databases are used to generate reports and develop models. Ownership clarity and sync policies are necessary for avoiding conflicts between accounts' statuses.
ML Inference and Decision Orchestration
Inference models predict factors like payment behavior and default probability for customers. Then an AI workflow orchestration system would combine these score values along with account statuses, operational priority levels, and rules for recommending actions. Outputs of models are for making decisions rather than granting permission to call on a borrower or changing their accounts.
Communication and Payment Services
The channel adapter connects a website or application to an authorized phone service provider for calls, text messages, emails, and chat services. Authorized payments are processed through a service provider that generates an authorization link for transactions while reconciling them against accounts. Idempotency of event management and control over retry attempts and fault detection help to avoid duplication of message delivery and payments.
Compliance Gate and Audit Service
A policy check is performed before any operation to verify the current status of accounts, relevant contacts' limitations on communications, communication boundaries, and necessary authorizations. Audit logs record input decisions, model version numbers, timestamp information, and actions taken by them. In case of failure to make payment on time or lack of necessary details, it will be stopped by the software and referred for further investigation.
Deployment and Scalability Considerations
Create independent scalability of applications to handle various types such as model predictions, messaging systems, and reports. A queuing system helps to handle surges of requests, whereas a retry mechanism and error handling improve reliability. Tenant isolation is needed for multi-client platforms to protect accounts from being accessed by other tenants; there might be requirements like regional deployment and data residency control due to contractual or jurisdiction-specific laws.
Planning to build an AI-powered debt collection platform tailored to your workflows?
Suffescom helps businesses explore custom AI development, system architecture, and secure integrations aligned with their collection requirements.
Data Requirements and Machine Learning Model Development
AI-based effective debt recovery requires precise information about accounts to make predictions correctly while having proper control of recommendation usage policies. The quality of data must be checked by models for automation purposes to take place first.
What Data Is Needed to Build AI Debt Collection Software?
Core data includes account balances, due dates, payment histories, delinquency stages, past interactions, promises to pay, repayment outcomes, and communication restrictions. Dispute and hardship flags are important to determine the eligibility of an action. Gather only required information and verify it for correctness of content, permission level, and allowed purposes.
Designing the Data Model
Organize this system based on those main components.
- Account and debt obligation: Balance sheet, liabilities, payment terms, and credit card balance information.
- Borrower and authorized contact: The authorized borrower and contact information are provided here for verification purposes.
- Payment and allocation: Transaction processing, payment management and settlement, billing cycle, invoicing process.
- Communication and interaction: channels, timestamps, and outcomes.
- Promise to pay and repayment arrangement: commitment of obligation satisfaction.
- Dispute, hardship, and compliance restriction: Case status and action limits.
- Model score and recommended action: Score of a model recommendation for prediction model version timestamp.
- Audit event: Decision approval execution process.
Use stable identifiers and historical records to reconstruct account state and decision history.
Preparing Data for Model Training
Remove duplicate entries, handle nulls, normalize timestamps, and check result tags. Specify prediction goals such as whether an account is eligible for a credit card payoff within 30 days. The historical snapshot feature and point-in-time correctness are used to prevent data leakage of future event information.
Selecting the Right Model
Select models based on available information for predicting outcomes and meeting business needs through operations management processes.
- A logistic regression model is an easy-to-understand starting point to predict payments.
- Gradient boosting models are good at modeling complicated relationships between variables within a dataset of accounts.
- Neural networks are worth evaluating when data volume and complexity justify additional costs.
Compare candidates to baselines by means of prediction accuracy, calibration quality, explainability level, and manufacturing needs.
Training, Validation, and Model Monitoring
A time-based split for training, validation, and testing is used so that it reflects actual production environment needs. Precision, recall, probability calibration, and performance analysis on relevant customer groups. Data monitoring for accuracy of models' performance; tracking changes over time; recovery rate after failure due to updates; process documentation.
It is important to note that predicting whether or not an investor will repay their loan does not guarantee any particular type of investment activity will result in debt settlement. Assess the efficacy of an intervention by means such as randomized trials or experimental studies. The NIST AI Risk Management Framework is an approach to manage risk associated with artificial intelligence during its implementation process.
How an AI Debt Collection System Works End to End
An AI-driven collection workflow connects and integrates customer information, database model, predictive analytics algorithm validation checker, messaging service, and transaction handling mechanism. Every stage should be based on up-to-date data, comply with relevant regulations, and have a traceable history.
Step 1: Ingest and Validate Account Data
Get import data for accounts via API integration of lending services like credit card companies' billing software to their customer relationship management system and payment processor event stream feeds. Check for validity of required fields, timestamp, and identifier; quarantine any invalid record.
Step 2: Determine Account Eligibility
Account balance, checkout history, payment details, dispute information, hardship flagging, and communications restriction. Implement appropriate regulations such as those under CFPB Regulation F. Halt operations if there are doubts about eligibility.
Step 3: Generate Predictions and Recommendations
Payment propensity score calculation, delinquency probability estimation, and expected recovery value prediction. Combine these predictions with account conditions and policy rules for recommending a suitable follow-up step. Predictions are used for prioritizing tasks; they don't have authority over them directly.
Step 4: Execute an Approved Communication or Workflow
Submit a validated template to an authorized source via email address. Log actions, timestamps, delivery statuses, and policy compliance. For escalating dispute resolution issues, hardships, request problems, and uncertainty situations as needed.
Step 5: Process Responses and Payment Events
Record borrower responses, promises of repayment, and notifications about payments. Match up to official transaction data for reconciliation of accounts; adjust balance sheets accordingly; delete duplicate notifications following successful payments. Idempotency of events prevents duplication during execution.
Step 6: Measure Outcomes and Review Performance
Recovery rate tracking, payment guarantee to date, turnaround time, complaint count, and expense per collection. Compare against a good baseline; perform an experiment if needed. Resolution of conflicts between routes; resolution failure for dispute settlement process; policy exception management by an authorized person.
Want to use AI to prioritize accounts and make smarter collection decisions?
Explore custom machine learning and predictive analytics solutions designed around your data, business rules, and measurable performance goals.
Integrations Required for AI Debt Collection Software
A debt management system powered by AI needs to be integrated with a database of accounts, a customer service department for handling customers' queries, a payment processing unit, and a reporting tool. Reliable fintech software integration ensures that accounts are up-to-date so as not to trigger false positives due to stale records or duplicate transactions.
Loan Servicing and Core Banking Systems
Connect with lending service providers' databases for balance information such as outstanding amounts, due date details, delinquent account statuses, and past payments, along with the owner of an account. API contract definition, data format specification, and synchronization protocol for collecting verified accounts from a database system.
CRM and Contact Center Platforms
Integration between CRMs and contact centers is used for syncing cases assigned by them to collectors' notes about calls made during conversations. Consistent account IDs and permissions will help avoid duplication of case data while allowing authorized collector access for viewing pertinent interaction information.
Payment Gateway and Banking Rails
Link a payment provider for hosting payment services like confirmation, failed transaction resolution, and the reconciliation process. Check for a valid signature on a webhook; use an idempotent key so that no duplicates are processed by it; perform reconciliations of payments against accounts' balance records.
Communication Providers
SMS, email, voice, and chat provider integration via standardized adapters. Track order statuses, errors, responses, and cancellation notifications. Use limited attempts for repeated failures of routing packets into a dead letter queue; also sync up on message delivery requirements prior to sending more ones.
Identity, Data, and Reporting Services
Identity Verification Authentication Services for Account Security Protection of User Data. Recovery statistics and models of performance analysis are available from analytical warehouse software as well as business intelligence applications for modeling purposes to analyze data sets over time. Integration failure monitoring, API latency detection, data freshness checks, and sync error reporting.
Regulatory Compliance and Responsible AI in Debt Collection
Compliance should be integrated into the workflow of a system for accessing information by users; the decision-making process should be based on an artificial intelligence model or auditing procedures. The requirements differ among organizations, types of debts, jurisdictions, and modes of communication. Therefore, a RULES engine is not sufficient for ensuring compliance.
Mapping Applicable Debt Collection Requirements
Assess for US-based companies the Fair Debt Collection Practices Act (FDCPA), applicable Regulation F regulations, and any other local legislation that may apply to them. Obligations related to communication, disclosure, dispute resolution, time-barred debt management, and records maintenance should be assigned according to workflow processes and roles of employees.
Building a Pre-Contact Compliance Engine
Before authorizing contact, evaluate account status, recent payments, dispute flags, contact history, applicable time and channel restrictions, and required disclosures. An engine must provide an answer like "approved," "blocked," or "needs further consideration." It also needs to note which rule was used for this decision-making process. Eligibility uncertainty must stop automatic actions.
Managing Disputes, Cease-Communication Requests, and Hardship Cases
Resolve disputes, stop communication requests, and make difficult cases an explicit account state with defined transition rules. Accordingly, depending upon their applicability and current state of affairs for each project, we may need to stop normal processes, limit certain types of access, or send it over to an expert for evaluation purposes. Only resume work once all requirements have been met.
Explainability and Auditability
Keep track of model versions, data input snapshots, or feature reference policy rules, recommendation approvals, and outcomes of actions taken. The documents are useful for investigating complaints by a team to understand decision-making processes and determine if they came from issues of data quality problems within model architecture, integration errors between systems, policy issues, etc.
Bias and Fairness Evaluation
Review poor representations, inaccurate labeling issues, and unsuitable proxies to be used during the model development process. Assess model effectiveness and results of data gathering among different types of customers for detecting unfairness towards them. Find out about document and study material differences; modify the model or decision rule as needed.
Human Oversight and Regulatory Change Management
Uncertainty in route prediction policies and exception disputes are sensitive cases for an authorized person. Manage an effective system of updating regulations through review processes such as impact analysis, amendment procedures, regression tests, approval mechanisms, and documentation release management. The NIST AI Risk Management Framework is useful for more comprehensive regulation of artificial intelligence; however, it doesn't substitute for a law review process.
Security, Privacy, and AI Governance
The AI debt collection platform handles confidential financial details as well as private data, so privacy protection is important right away. Implement security measures such as data privacy policies and authentication mechanisms for accessing systems and logging activities of models during both stages (development and deployment).
Encryption and Sensitive Financial Data Protection
Data encryption is done in transmission as well as storage through standard protocols. Securely manage encryption keys and application secrets; limit access to them; gather only what is needed for legitimate business needs. Retention policy for financial record-keeping, history management system, and data privacy rules on artificial intelligence-generated material.
Role-Based Access Control and Tenant Isolation
Implement least privilege access and role-based permissions for collector, administrator, analyst, and AI service users. Assign separate responsibilities to handle sensitive tasks; periodically check the privileges of users accessing them; set up individual privacy zones within a common network infrastructure.
Secure AI and LLM Integration
To protect an AI workflow from being hacked by malicious input or leaked information to third parties. Implement security measures for retrieving data; verify results from models before using them; and limit the functionality of software applications to specific permissions granted by administrators.
Audit Logging, Retention, and Incident Response
Audit authentication, data access, policy decisions, model versions, and administrative changes. Define configurations for security alerts, retention schedules, and incident response procedures. Maintain documented and tested backup, recovery, and rollback procedures to restore service operations and investigate incidents.
Leverage the NIST AI Risk Management Framework’s four functions to organize ongoing governance around the AI lifecycle. Rather than a one-time assessment, apply the Govern, Map, Measure, and Manage functions as a continuous process to operate and refine the model over time.
Struggling to connect your collection platform with existing financial systems?
Suffescom's AI integration capabilities can help assess API connectivity, legacy systems, data flows, and workflow automation requirements.
AI Debt Collection Software Development Process
A rigorous software development process supports teams in transitioning from business requirements to a production-ready platform that delivers on security, measurement, and risk control promises. Formalize requirements and define acceptance criteria for each phase to ensure alignment before proceeding to the next stage.
1. Define Requirements and Collection Workflows
Document target portfolios, user roles, account states, system integrations, and desired business outcomes. Agree upon collection workflows, obligations, exception routes, and recovery or success metrics like recovery rate and cost to collect.
2. Audit Data Readiness and Integration Constraints
Perform a discovery and readiness assessment to understand historical data representativeness, outcome coverage, system ownership, API availability, and synchronization constraints. Identify reconciliation requirements, missing records, exceptions, and constraints that could impact model performance or automation.
3. Design the Architecture and Security Controls
Define service boundaries, deployment options, storage, event ingestion, authentication, and tenant isolation requirements. Determine the policy engine’s role in managing AI recommendations or communications.
4. Build the MVP and Core Workflow Engine
Implement account management, collection queues, approved communication channels, payment tracking, permissions, and reporting capabilities. Design the system around reliable workflows and audit trails before adding AI capabilities.
5. Develop and Validate AI Models
Build and validate baseline models for payment likelihood or delinquency prediction. Define evaluation metrics, validate historical performance, check calibration and subgroup outcomes, and thoroughly document limitations before launch.
6. Integrate Communication and Payment Services
Design and test integrations with messaging providers, payment processors, and servicing systems. Confirm webhook verification, idempotency, retries, failure alerts, and reconciliation processes before enabling production use cases.
7. Pilot with Human Oversight
Launch the platform in a limited capacity to validate performance against an appropriate baseline. Evaluate the impact on prediction accuracy, customer complaints, payment outcomes, policy exceptions, and overrides before wider adoption.
8. Deliver, Observe, and Improve
Leverage staged rollouts, versioned models, operational alerts, rollback procedures, and controlled retraining. Continuously observe the platform’s ability to meet compliance, security, and business requirements as portfolios, regulations, or policies change.
Testing and Quality Assurance for AI Debt Collection Software
A testing and quality assurance process should ensure accuracy in financial record-keeping and collection practices, verify that the platform adheres to required collection workflows, and confirm that unauthorized collection actions are prevented or appropriately escalated. At a minimum, test individual components and end-to-end scenarios that exercise critical production capabilities.
Functional and Workflow Testing
Test account lifecycle transitions, payment arrangement creation, collector permissions, and exception routing logic. Confirm that payments update account balances and that disputed or restricted accounts follow appropriate collection pathways.
Integration and Reconciliation Testing
Simulate webhook duplicates, event delays, payment failures, API timeouts, and service outages. Ensure that idempotency keys prevent duplicate processing and that reconciliation jobs detect discrepancies between payment providers and account records.
AI Model Testing
Evaluate prediction accuracy, probability calibration, subgroup performance, and sensitivity to changing conditions. Use holdout sets to confirm generalization beyond training data and define model monitoring thresholds for production use cases.
Compliance and Adversarial Testing
Test restricted-contact scenarios, disputed accounts, incorrect account balances, and missing required disclosures. For large language models, test prompt injection attempts, data retention, and attempts to access unauthorized features. Verify that policy checks block prohibited collection actions and that questionable cases are appropriately escalated for review.
Load, Reliability, and Recovery Testing
Confirm message queue performance, system response characteristics, and recovery behaviors under normal and peak conditions. Verify backup and restore processes, retry logic, and recovery point objectives to ensure that platform outages do not create downstream duplicates or accounting errors.
How to Measure AI Debt Collection Performance?
Measure performance using financial, operational, engagement, model, and compliance metrics to ensure that the debt collection solution meets business goals. Define metrics with consistent calculation methods, establish informative baselines, and compare performance across similar portfolios and time intervals.
Recovery Rate
Calculate the ratio of funds recovered to eligible outstanding balances for a given portfolio and time period using a consistent methodology. Define how new account funding, adjustments, and write-offs affect the calculation to enable meaningful comparisons between dates or portfolios.
Roll Rate and Delinquency Resolution
Calculate first-time cure rates and resolution percentages for accounts or dollars moved from one delinquency state to the next (i.e., 30-day delinquency to 60-day delinquency). Monitor trends to demonstrate improvements or declines in the collector’s ability to resolve delinquencies.
Cost-to-Collect
Measure collection costs as a ratio to dollars recovered using a consistent definition (i.e., cost per dollar recovered). When evaluating changes over time or comparisons between portfolios, consider the suite of costs associated with collection activities or technology investments that drive recovery outcomes.
Promise-to-Pay Fulfillment
Calculate the percentage of collector-promised payers that fulfill the promise within the agreed time frame. Track missed promises, partial payments, and fulfilled arrangements to understand downstream follow-up and recovery outcomes.
Contact and Digital Engagement Metrics
Measure right-party contact, if available, and response rates for different communication channels. Track message delivery and self-service portal usage rates for an engagement metric that reflects customer sentiment and resolution rather than raw volume.
Model and Compliance Metrics
Monitor calibration, override rates, restricted-contact use, complaint ratios, and staff escalation outcomes to identify areas of improvement. Regularly review model exceptions to ensure that automated recommendations yield benefits without unintended consequences for compliance or customer experience.
AI debt collection KPI table
| Metric | Example formula | Data source | Review frequency |
| Recovery rate | Amount recovered ÷ defined eligible balance | Servicing and payment records | Weekly or monthly |
| Roll rate | Accounts entering next delinquency stage ÷ accounts at starting stage | Account history | Monthly |
| Cost-to-collect | Collection operating cost ÷ amount recovered | Finance and operations | Monthly |
| PTP fulfillment | Promises fulfilled as agreed ÷ eligible promises due | Promise-to-pay records | Weekly or monthly |
| Contact success | Successful right-party contacts ÷ eligible contact attempts | Contact center and CRM | Weekly |
| Model calibration | Predicted probabilities compared with observed outcomes | Model monitoring data | Monthly or by volume threshold |
| Restriction violations | Confirmed violations of applicable restrictions | Compliance and audit logs | Continuous monitoring |
| Human escalation rate | Cases escalated for review ÷ cases processed | Workflow logs | Weekly |
Challenges in AI-Powered Debt Collection and How to Solve Them
Beyond developing the machine learning models themselves, organizations must also consider how to overcome additional challenges in building AI-powered debt collection systems. Data availability, legacy system integration, unreliable predictions, and evolving regulations can all impact an organization’s ability to successfully adopt AI-driven solutions. The following recommendations highlight approaches for overcoming these barriers to successful AI implementation.
Poor or Incomplete Historical Data
Inadequate historical information about account features, payments, or collection outcomes can reduce an organization’s ability to train accurate or useful models. Before launching AI initiatives, address data quality concerns, label validation issues, and unreliable historical baselines.
Legacy System Integration
Legacy servicing systems and banking infrastructure can introduce significant integration and synchronization challenges when implementing new AI-driven tools. To reduce the risks and costs associated with integration, utilize available adapters and adopt synchronization processes that align with the capabilities of older systems.
Model Drift and Unreliable Predictions
The models may be affected by changes in borrower behavior, the portfolio, or the economy. Monitor performance and calibration, establish retraining limits, and compare new models against the existing production model. Continue with the rollback process to safely interchange models that are not meeting expectations.
Over-Automation and Borrower Friction
You can end up sending the wrong reminders, understanding what was asked incorrectly, or reacting to a sensitive situation awkwardly if you over-automate. Route disputes, hardship cases, messages that may be unclear, and staff judgment are required. Implement verified borrower info, accepted communication templates, and clearly defined escalation procedures to ensure proper borrower experiences.
Regulatory and operational complexity
There are variations in requirements from jurisdiction to jurisdiction and from channel to channel, depending on the type of debt. Ensure policies are up-to-date, have clear ownership, and undergo scenario testing that applies prior to publishing. Track approvals and audit results, and consult with relevant compliance or legal experts on policy changes.
AI-Powered Debt Collection Software Development Cost and Timeline
The cost of AI debt collection software can vary depending on several factors, such as the software's features, complexity of integration, AI capabilities, security features, and the size of the deployment. The custom solution can range from about $50,000 for a simple MVP to $500,000, or even higher, for an enterprise platform. These are indicative figures and not a formal quote.
MVP vs. Enterprise Platform Scope
The ranges can be used as guidelines for custom projects. Actual costs depend on the extent of work agreed to and the delivery team and integration needs.
| Solution type | Estimated development cost | Indicative timeline | Typical scope |
| Basic MVP | $50,000–$100,000 | 3–5 months | Account management, collection queues, approved reminders, payment tracking, basic reporting, and essential integrations |
| AI-powered platform | $100,000–$250,000 | 5–8 months | Predictive scoring, workflow automation, multiple communication channels, analytics, and expanded integrations |
| Enterprise platform | $250,000–$500,000+ | 9–12+ months | Multi-tenant architecture, advanced AI, high-volume processing, extensive integrations, governance, and enterprise security |
These are representative planning ranges only and are not prices being offered by Suffescom. The total cost can range up to $500,000 or even more if the business has a complex integration requirement, needs extensive custom AI, or has a demanding operational requirement.
Key Cost Drivers
The amount of development money that will be available will be dependent upon several factors:
- Large account volume: Dealing with large volumes of accounts requires increased capacity, monitoring, and performance optimization.
- Integrations: Loan servicing, CRMs, communication providers, and payment gateways contribute to the engineering and testing process.
- The complexity of AI: Basic payment propensity models take less work than multiple predictive models, collection optimization, and conversational AI.
- Data readiness: There might be some incomplete historical data, which requires additional data cleaning, labeling, and pipelines.
- Security and compliance: Encryption and access controls, audit trails, jurisdiction-specific policies, and testing, among other things, are part of the implementation costs.
- Requirements for deployment: Infrastructure and engineering effort may escalate during deployment for multi-tenant, HA, data residency, and disaster recovery.
Development Timeline and Delivery Phases
Development usually follows the stages of discovery, architecture, core engineering, integration, AI validation, pilot, and production rollout. A basic MVP can be implemented in around 3-5 months, while the larger-scale implementation of AI could take 6-12 months or longer.
The timeline could be impacted by data availability, access to existing systems, regulatory review, and tests. Teams may develop some parts simultaneously; deployment to production will wait until critical integration, security, and compliance pass.
Ongoing Operating Costs
Development is just a component of the overall cost of ownership. Another area that companies should budget for is:
- Reliable cloud infrastructure: Compute, databases, storage, backup, and scaling.
- Communication services: SMS, email, voice, and contact center provider fees.
- Payment Processing: Gateway or transaction fees (if applicable).
- AI operations: Model inference, use of LLM, monitoring, and retraining.
- Maintenance and security: Bug fixes, dependency updates, penetration testing, and incident response.
- Compliance and support: Keeping abreast of regulatory changes, policy testing, auditing, etc., and technical support.
Unsure how much it will cost to develop your AI debt collection software?
Define your MVP scope, required integrations, AI capabilities, and deployment needs to establish a realistic development roadmap and budget.
Build vs. Buy AI Debt Collection Software
If the workflow is more complicated, there is a need for more integration, limited internal expertise, or cost, then a custom-built system may be more beneficial than using an existing platform. Compare options according to their suitability for your business needs, your compliance requirements, and the level of control your business needs.
Build or Buy or Hybrid: Decision Matrix
| Decision factor | Custom build | Existing platform | Hybrid approach |
| Initial implementation | Usually higher effort | Often faster | Moderate, depending on extensions |
| Workflow flexibility | High | Depends on vendor | High for selected components |
| Integration control | Full design control | Depends on available connectors | Shared between platform and custom services |
| Ongoing maintenance | Internal responsibility | Shared with vendor, depending on contract | Split across vendor and internal teams |
| AI customization | High | Depends on built-in capabilities | High for selected AI services |
| Best suited for | Distinctive requirements and strategic ownership | Standard workflows and faster deployment | Existing platforms needing targeted customization |
When Custom Development Makes Sense
Custom development will be a fit for businesses with different workflows, integrations, portfolio-specific models, security, and governance needs. It offers greater freedom in product and architecture development but requires ongoing investment in model operations, testing, engineering, and infrastructure.
When Buying an Existing Platform Makes Sense
For organizations with a more predictable collection process, an existing platform might be more appropriate, as it can be implemented more quickly. Current account management, communication, reporting, and compliance functionality may reduce development time. Prior to the decision, research potential for customization, compatibility, security from the vendor, cost, and data portability.
A Hybrid Approach: Configure and Extend
Hybrid is a combination of an existing collections platform and a dedicated service for predictive scoring, decision orchestration, analytics, or conversational AI. This can be useful in expediting implementation while at the same time keeping flexibility in mind when differentiation is necessary. Clear service boundaries and permissions are outlined and enforced, and audits and compliance controls for custom components are followed.
How to Compare Total Cost of Ownership
Comparing costs is not only about initial development or subscription fees but also about a fixed period of time. Make sure licensing, engineering, integrations, cloud infrastructure, security, compliance updates, monitoring model, support, upgrades, and eventual migration costs are covered. Use a formula to determine the maintenance costs, as well as implementation costs, and understand the long-term commitment.
Future of AI-Powered Debt Collection
Going forward, AI-based debt collection could see additional real-time decision-making capabilities, improved granularity in automation, and better model management. The goal will be to render the collection processes more responsive and measurable, but not entirely without the involvement of humans.
Agentic AI for Bounded Collection Workflows
Agentic AI can help to coordinate approved items such as account details, case content, update case records, and even forward exceptions. Tool permissions should be restricted; check policy and ask for human permission for sensitive actions in production systems.
Real-Time Decisioning and Event-Driven Collections
Event-driven systems can react to payment confirmations, missed installments, borrower responses, and account-status changes as they happen. If events are validated and reconciled, fresher information enables the decision engine to provide more up-to-date advice and reduce needless follow-ups.
More Explainable and Governed AI Systems
Future platforms will require robust decision traceability, versioned models, ongoing checks, and risk measures that can be quantified. Keeping track of model output, policy evaluation, and performed actions will assist teams to explore errors and provide evidence of the decisions that were automated.
Personalized Payment Plans and Next-Best-Action Recommendations
AI systems can make increasingly intelligent recommendations for appropriate follow-up steps based on account history, payment behavior, the borrower's response to an offer, and accepted policy parameters. A next-best-action engine can prioritize some of the actions you can take, like sending a reminder or referring an account to a specialist. Eligibility rules should not be incorporated into predictive scores, and the affordability factors and necessary approvals should be distinct.
Continuous Learning Through Collection Outcomes
Future models will be able to measure their effectiveness through verification of results such as successful transactions, failed commitments, conflicts between parties, and customer service interactions for improvement purposes. Pipeline for feedback validation of labeling process detection to prevent leakage between datasets and comparison of model performance in a live environment vs. historical dataset. Only promote new versions of software after they have been tested on paper for safety reasons.
Why Choose Suffescom for AI Debt Collection Software Development?
Creating a debt collection system needs more than just prediction algorithms. This is a combination of finance management systems integration, security controls, automated processes, and monitoring models' performance over time. Our AI development services are available for those needs.
Custom AI and ML Engineering
Our AI/ML development services are for data pre-processing, feature engineering, and custom model-building. They may be used for predicting payment behavior, detecting defaults, and prioritizing accounts based on the availability of information as well as the specific requirements of each project.
Financial Software Integration Expertise
API-based integration and legacy system upgrades are part of our AI integration services. These features are applicable for integrating service provider management software, customer relationship management system (CRM) solutions, billing platforms, and messaging gateways, among others, along with their respective reliability standards and security needs identified through an initial assessment process.
End-to-End Delivery and Support Services
Discovery, data preparation, model development, integration, testing, machine learning development, and operations monitoring are our core after-sale services. Our AI development portfolio is a collection of projects from related fields that demonstrate some aspects of our wider technological capabilities. A debt collection engagement should establish specific deliverables, acceptance criteria, security controls, and post-launch support requirements.
Secure and Scalable Platform Architecture
Debt recovery software powered by AI needs to handle confidential banking information and email logs of customers' interactions with it companies for processing payments efficiently. Suffescom is able to design an extensible framework for securing APIs through authentication mechanisms such as role management, encryption of information transfer channels between systems or applications, auditing logs, and integration resilience.
Intelligent Workflow Automation and Conversational AI
Automation of routine data gathering is not just about sending emails. AI helps categorize borrowers' answers, summarizes conversations, recommends next steps for follow-up on issue situations, and routes them out of the system by way of a human agent. Suffescom's AI development services include AI, chatbot technology, and process optimization solutions, which may be tested on them to see if they are suitable for those purposes.
Model Monitoring and Continuous Optimization
The debt collection model needs to be evaluated continuously due to changes in customers' payment habits, their portfolios, and borrowers’ behaviors over time. A well-planned implementation can include model performance dashboards, drift detection, version control, retraining workflows, and rollback procedures. The suggested scope of service by Suffescom includes defining monitoring duties and setting up metrics to measure productivity levels, as well as approving changes made to models.
Ready to turn your debt collection software idea into a production-ready solution?
Work with Suffescom to explore custom AI development, secure architecture, integration planning, and ongoing model optimization for your use case.
Conclusion
AI-powered debt collection system development involves much more than just prediction algorithms and automatic notifications. Accurate accounting information is reliable; prediction algorithms are used to recommend policies that comply with regulations through a set of pre-determined guidelines. The compliance and security of information systems should include an audit trail to allow human intervention at an early stage.
Reliability of production is dependent upon the security integration process for payments, reconciled regularly by us to ensure smooth operation through constant surveillance tests conducted periodically. Selecting from customization options to use an off-the-shelf product versus a combination thereof involves assessing business requirements such as functionality, compatibility issues, scalability concerns, and overall expenses associated with it.
For businesses looking at developing their own solutions, they should consider using Suffescom's AI development services so that it would be an appropriate technology choice, design model, and deployment needed for an effective debt management system.
FAQs
What is AI-powered debt collection?
With AI-based collections management systems, companies can automate their processes for managing delinquent debts through machine learning algorithms and other technologies like natural language processing or predictive analytics. This is useful for prioritizing accounts and predicting customers' payment behavior.
How Does AI Improve Debt Collection?
AI analyzes payment histories, account characteristics, and interaction outcomes to identify patterns and prioritize accounts. Workflow automation reduces repetition of tasks, whereas prediction helps to choose suitable next steps for a team member. The actual result depends upon data quality, portfolio characteristics, implementation process, and operations of a company.
How Do You Build AI Debt Collection Software?
Define a workflow for collecting data; define business needs; specify regulatory restrictions on it. Prepare historical account and payment data, design the system architecture, develop and validate predictive models, and integrate servicing, CRM, payment, and communication systems.
What Data Is Needed for AI Debt Collection?
Typical inputs include payment history, outstanding balances, account status, delinquency records, previous collection attempts, communication responses, and promise-to-pay outcomes. Conflict resolution issues, difficulty of access problems, communication barriers, and billing procedures are also relevant to deciding on appropriate measures.
Can AI Debt Collection Software Integrate With Existing Systems?
Yes. Integration may be done through REST API calls, webhook notifications, stream events, and scheduled bulk data exports based on what is available from current applications. Loan servicing platforms, CRM systems for customer relationship management, payment gateway service providers, and communication companies are some of them. Idempotent transactions are reconciled through retries, while errors are monitored for consistency of accounts and payments.
How Much Does AI Debt Collection Software Development Cost?
The price of a custom-made product can range from around $50,000 up to $500,000+ based on its specifications. An entry-level product usually has a lower cost compared to a business application that includes sophisticated machine learning algorithms, chatbot functionality, complex integration capabilities, and a high level of protection measures.
Is AI Debt Collection Software Compliant by Default?
No. Compliance is based on relevant regulations of law, types of debts, jurisdictions, communication methods, and system configurations. US consumer debt collection laws such as the Fair Debt Collection Practices Act and Regulation F are applicable for this purpose; platforms must have contact restrictions, handle disputes effectively, keep records of transactions, and be reviewed regularly by qualified compliance and legal experts.
Can AI Negotiate Repayment Plans Automatically?
AI helps to manage an eligible repayment process by providing available choices, verifying set boundaries, and forwarding applications towards approval. Plan automation must be allowed under relevant laws, contracts, and company policy. Dispute matters, hardship cases, exceptions, and decisions need to be referred by an employee for further action.
Which AI Models Are Used in Debt Collection Software?
Common approaches include classification models for delinquency prediction, gradient-boosted trees for payment propensity, and time-to-event models for estimating payment timing. Natural language processing can classify borrower messages, while large language models can summarize interactions or draft approved responses. Model selection depends on available data, explainability requirements, and the intended use case.
How Long Does It Take to Develop AI Debt Collection Software?
A basic MVP may take around three to five months, while a broader AI-powered platform may require five to eight months. Enterprise implementations can take nine to twelve months or longer. These are indicative estimates; data preparation, legacy integrations, compliance reviews, and testing can significantly affect delivery time.
How Do You Measure AI Debt Collection Software Performance?
Track recovery rate, roll rates, cost-to-collect, promise-to-pay fulfillment, and time to resolution. Also monitor contact effectiveness, prediction calibration, complaint rates, compliance exceptions, and model drift. Compare results against suitable historical baselines or controlled pilots to distinguish genuine improvements from changes in portfolio composition or collection conditions.
Should Businesses Build Custom AI Debt Collection Software or Buy an Existing Platform?
Custom development suits businesses that need specialized workflows, proprietary decision logic, or greater control over integrations and data. Existing platforms can accelerate implementation when standard features meet operational needs. A hybrid approach combines a commercial platform with custom AI components. Compare total ownership costs, security, scalability, customization, and vendor lock-in before deciding.