Key Takeaways:
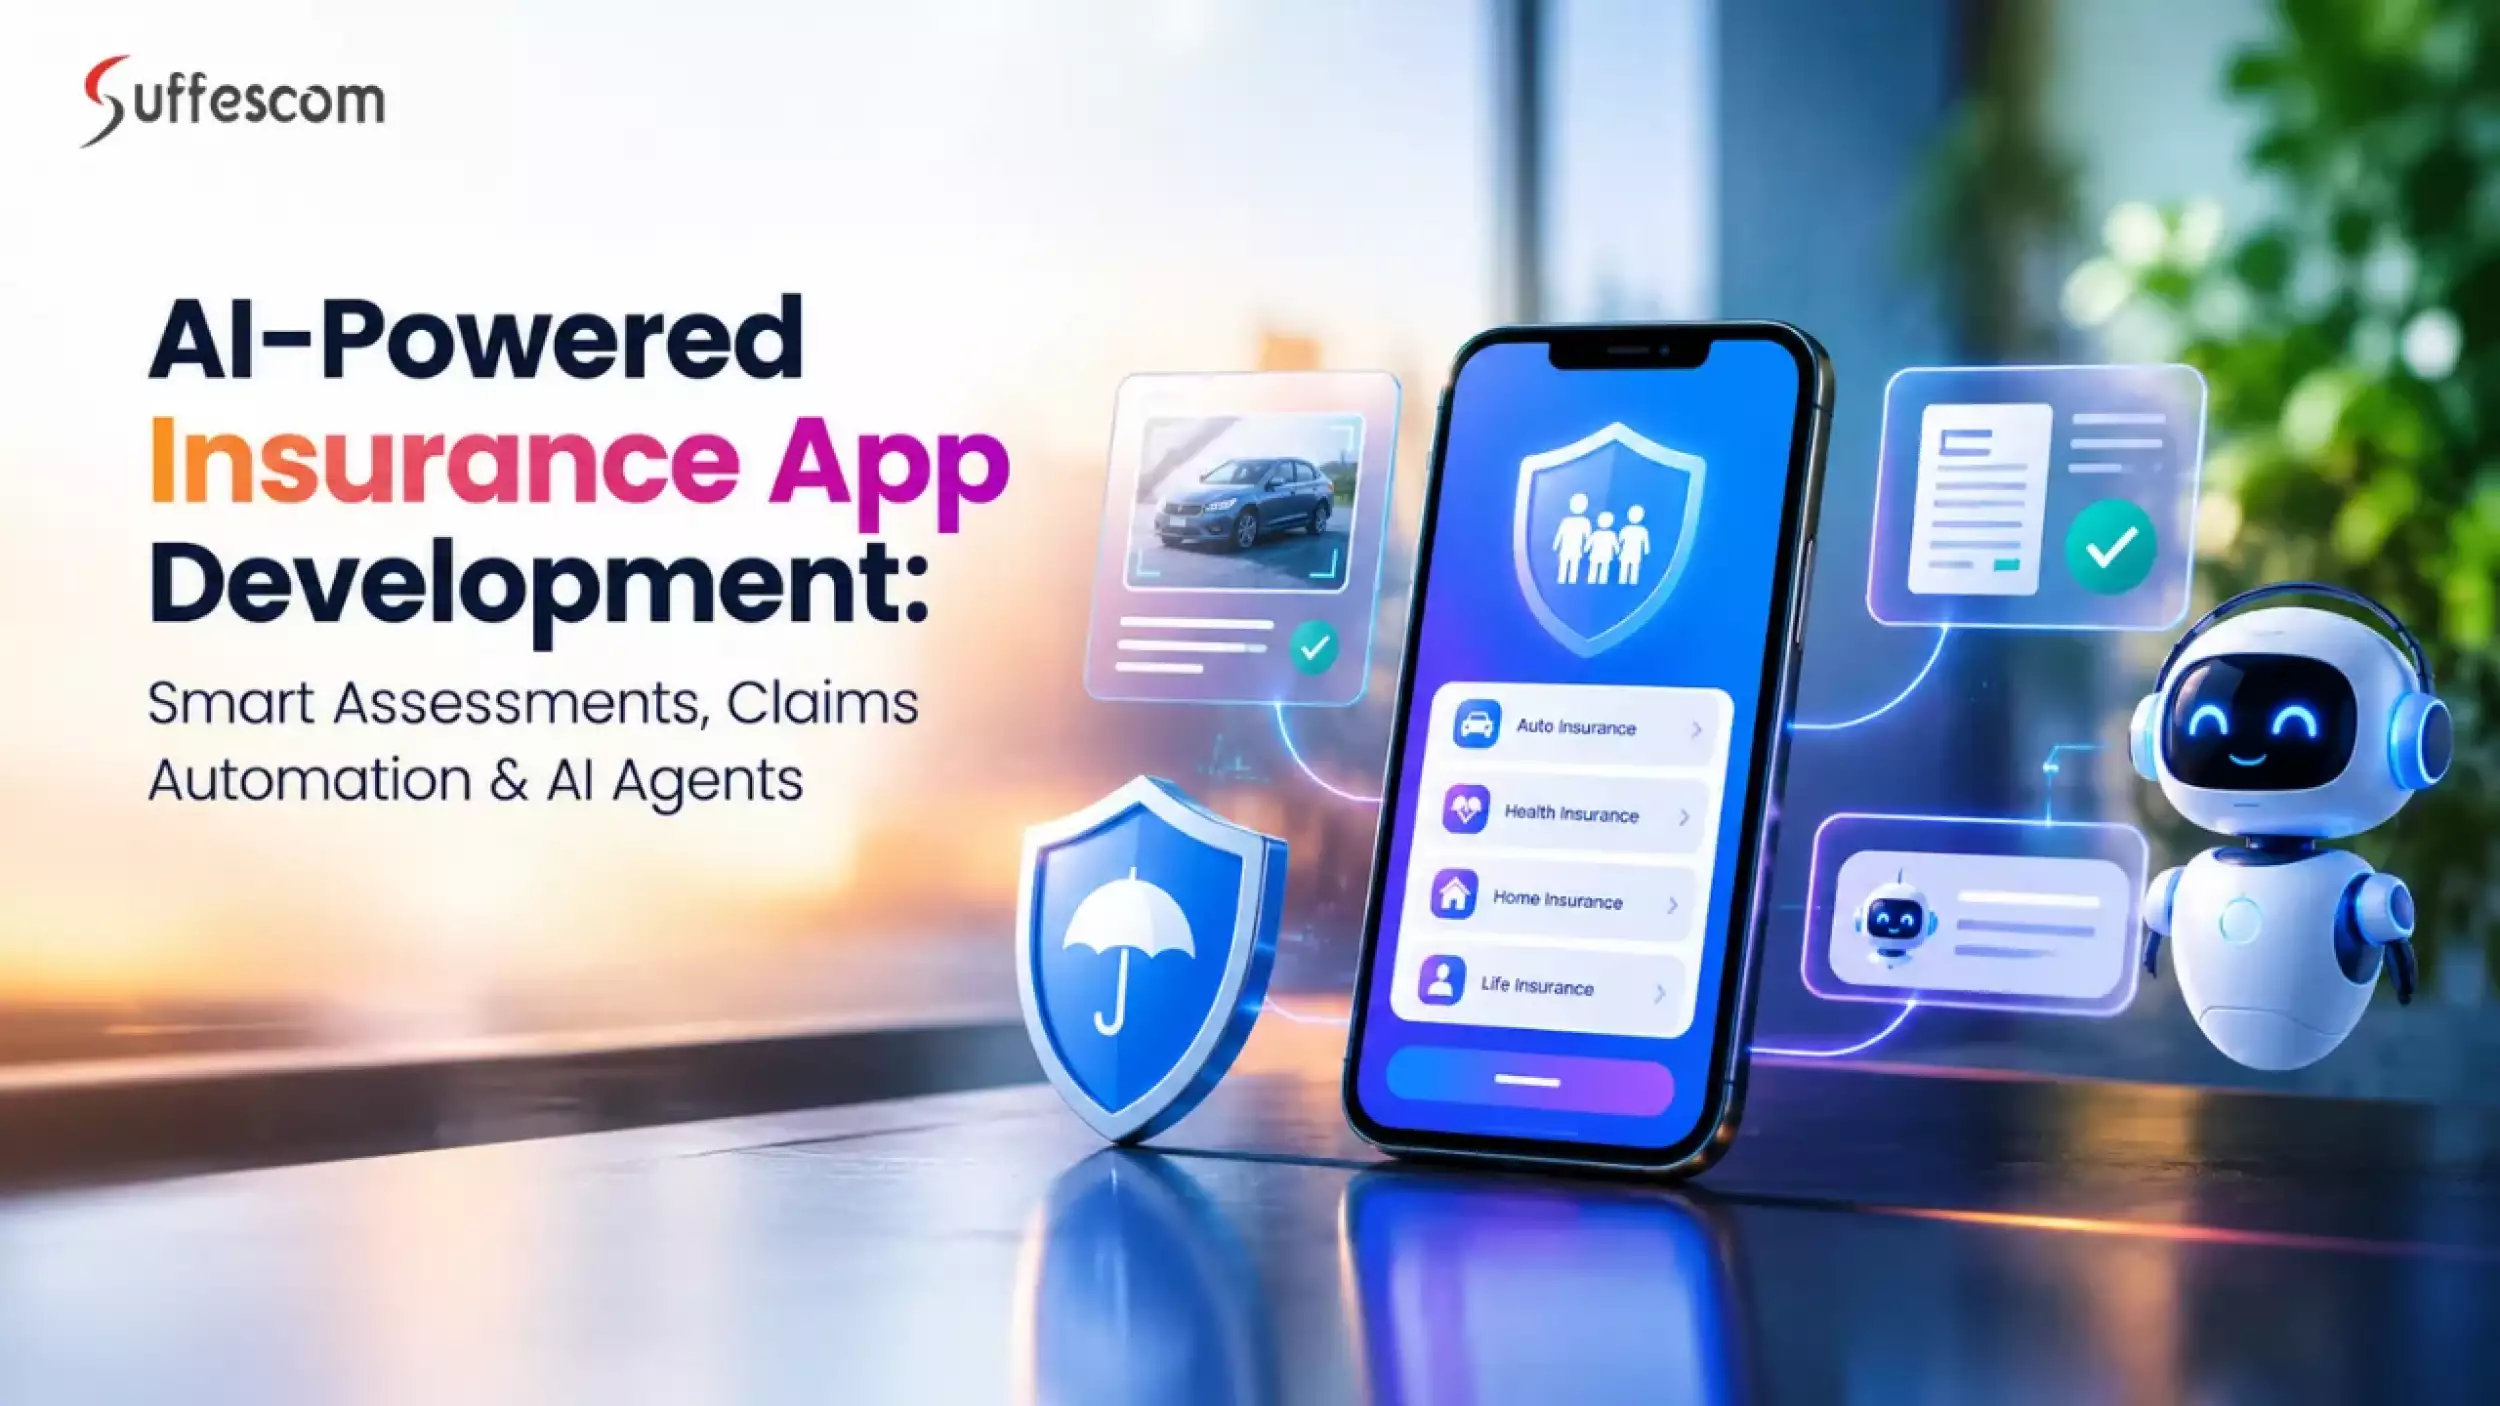
- AI-powered insurance apps use machine learning, computer vision, and generative AI to improve risk assessment, claims handling, policy management, and customer service.
- AI insurance measurement apps analyze vehicle or asset images to identify damage, support measurements, and generate preliminary repair estimates.
- AI agents can coordinate multi-step insurance workflows, from collecting claim documents to checking policy details and routing cases for review.
- AI insurance app development costs can range from approximately $30,000 for a focused solution to $500,000 or more for a complex, integrated platform.
- Successful implementation depends on reliable insurance data, secure system integrations, model validation, and appropriate human oversight.
Insurance operations involve large volumes of policy documents, customer information, risk assessments, inspection reports, and claims records. Processing this information manually can slow decisions, increase administrative workloads, and make it difficult to deliver consistent customer experiences. AI-powered insurance app development offers a way to improve these workflows by combining intelligent data processing, predictive analytics, and automation in a single digital platform.
AI adoption is also moving beyond basic customer service. According to McKinsey's research on AI in the insurance industry, Aviva used more than 80 AI models in its motor claims operations, reducing liability assessment time for complex cases by 23 days and improving the accuracy of claim routing by 30%. These results demonstrate how targeted AI implementations can improve specific insurance processes.
For insurers, insurtech startups, brokers, and third-party administrators, the opportunity extends across the insurance lifecycle. An AI-powered app can help assess risk, analyze damage evidence, automate claim-related tasks, and provide policyholders with faster access to information. AI agents add another layer by coordinating tasks across multiple systems while keeping important decisions subject to defined business rules and human review.
Developing an effective solution starts with identifying the insurance workflows that need improvement, selecting appropriate AI capabilities, and integrating them with the organization's existing systems.
Overview of AI-Powered Insurance App and How Does It Work?
An AI-powered insurance app is a digital application that uses artificial intelligence to interpret insurance data, generate predictions or recommendations, and automate selected operational tasks. It can serve policyholders through a mobile app, support employees through an internal platform, or connect multiple insurance systems through a shared backend.
Unlike a conventional insurance app that primarily displays policy information and collects forms, an AI-enabled platform can analyze submitted documents, identify relevant information, flag inconsistencies, and help route cases to the appropriate team.
How the AI workflow operates
- Data collection: The app receives information from policy forms, customer submissions, images, inspection reports, claim records, and connected business systems.
- Data processing: Document processing with optical character recognition (OCR), document intelligence, and validation rules extract relevant information and identify missing or inconsistent fields
- AI analysis: Machine learning models assess patterns, computer vision examines images, and language models interpret policy documents or summarize case information.
- Workflow execution: The platform recommends an action, routes the case, requests missing information, or initiates an approved task.
- Review and feedback: Employees review cases requiring judgment, while operational outcomes help teams evaluate and improve model performance.
The architecture depends on the intended application. A photo-based motor insurance assessment app may prioritize computer vision, while a claims automation platform may need document intelligence, policy-system integration, and workflow orchestration.
Which Insurance Operations Can AI Apps Transform?
AI creates the most value when it addresses a defined operational bottleneck rather than being added as a standalone feature. The following applications illustrate how insurers can use AI across different stages of the insurance lifecycle.
AI-Powered Risk Assessment and Underwriting
Underwriting teams evaluate information about applicants, insured assets, coverage requirements, and potential losses before deciding whether to offer a policy and on what terms. AI models can analyze historical claims, property characteristics, vehicle details, business records, and other permitted data to identify risk patterns.
The application can organize supporting evidence, flag unusual information, and generate a risk summary for an underwriter. Predictive models may also support pricing analysis when trained on appropriate data and validated against the insurer's underwriting criteria.
AI should support rather than automatically replace underwriting judgment. Decisions involving eligibility, pricing, or coverage need appropriate controls, explainability, and compliance with applicable insurance rules.
Automated Claims Intake, Validation, and Processing
Claims processing often requires information to be collected from several sources before a claim can progress. An AI-enabled platform can extract information from forms, invoices, police reports, medical documents, and other supporting evidence. It can compare submitted information with required fields and identify missing documents.
Once the claim record is assembled, workflow rules can route it according to claim type, completeness, severity, or other approved criteria. Straightforward cases may move through predefined processing steps, while inconsistent, high-value, or potentially disputed claims can be escalated.
Insurers planning this capability can review AI insurance claims processing platform development for a solution focused on automating claims-related workflows. For a deeper explanation of the process, the guide to AI insurance claims processing provides additional context.
Personalized Policy Recommendations and Premium Estimation
AI can help insurers and digital brokers match customer requirements with relevant policy options. A system can analyze declared coverage needs, eligible product criteria, previous interactions, and other authorized information to present suitable options.
For premium estimation, predictive models can support calculations using approved rating factors and insurer-defined pricing rules. The app can explain the factors used in an estimate and distinguish indicative quotes from confirmed offers.
Personalization must respect customer consent, data protection requirements, and restrictions on the use of sensitive attributes. Recommendations should be traceable to the relevant product rules rather than generated without constraints.
Fraud Detection and Suspicious Claim Identification
AI-powered fraud detection software can examine patterns across claims, transactions, documents, and historical records to identify anomalies that warrant further investigation. For example, a model may flag repeated claim patterns, inconsistencies between submitted documents, or unusual relationships between records.
These signals help investigation teams prioritize their workload. However, an anomaly does not prove fraud. The app should record why a case was flagged and route it for appropriate review instead of automatically rejecting a legitimate claim based only on a model score.
AI-Powered Customer Support and Policy Assistance
Policyholders frequently need help understanding coverage terms, deductibles, renewal dates, exclusions, claim requirements, and application status. An AI assistant can answer routine questions using approved policy documents and verified account information.
A well-designed system can retrieve the relevant policy clause, summarize it in accessible language, and direct the customer to the appropriate action. If the question involves a disputed claim, unclear coverage, or a sensitive decision, it should transfer the conversation to an authorized employee.
How AI Agents Are Changing Insurance Workflows
AI agents are software systems designed to interpret a goal, determine the next steps, use approved tools, and coordinate tasks with limited human intervention. In insurance, this makes them useful for workflows that involve multiple documents, systems, and handoffs.
A conventional chatbot generally responds to a user's question. An AI agent can go further by checking information, initiating permitted actions, monitoring progress, and reporting the result.
AI Agents for Claims Intake and Triage
A claims agent can collect initial information, check whether required documents have been submitted, retrieve relevant policy details, and classify a claim for routing. If information is missing, it can prepare a request for the policyholder.
For example, when a motor insurance claim arrives, the agent might assemble the claim details, identify missing photographs, check the applicable policy record, and prepare a case summary for the claims team. The actual coverage decision or settlement approval remains subject to the insurer's rules and approval process.
AI Agents for Policyholder Queries
A policy assistance agent can retrieve policy information, explain common terms, provide renewal reminders, and guide customers through claim submission. With suitable authentication and permissions, it can also retrieve account-specific information or initiate approved service requests.
Its responses should be grounded in current policy documents and account records. If it cannot verify an answer, it should acknowledge the limitation instead of inventing coverage details.
AI Agents for Underwriting Support
An underwriting agent can collect information from submitted applications, summarize relevant evidence, identify missing fields, and prepare a risk brief for an underwriter. It can also retrieve supporting information from approved internal sources.
This reduces time spent gathering and organizing information. The underwriter remains responsible for interpreting the evidence and making decisions according to the insurer's policies and applicable regulations.
AI Agents for Document Follow-Ups and Workflow Coordination
Some insurance processes stall because a customer, repair provider, broker, or internal team has not supplied the required information. An AI agent can monitor workflow status, identify outstanding tasks, draft reminders, and update task records when permitted.
To build these capabilities, insurers can consider AI agent development services for agents designed around specific business workflows. The implementation should define what an agent can read, change, approve, or escalate before it is connected to live insurance systems.
Inside an AI Insurance Measurement App: From Images to Damage Estimates
AI insurance measurement apps use image analysis and related data to support the inspection and assessment of insured assets. They are particularly relevant to motor and property insurance, where photographs, measurements, and repair estimates can influence the next steps in a claim.
The exact capabilities depend on the asset type, image quality, available reference data, and the level of measurement accuracy required.
Photo and Video Capture for Vehicle or Property Inspections
The app can guide a customer, field inspector, or repair professional through a structured image-capture process. Instructions may specify the required angles, distance, lighting, and areas to photograph.
Automated checks can identify blurred, dark, incomplete, or duplicate images and prompt the user to submit clearer evidence. This improves the quality of information available for subsequent analysis.
Computer Vision for Damage Detection and Classification
Computer vision models can identify visible damage, such as dents, scratches, cracks, broken components, or signs of property deterioration. The model may classify the affected area and generate an annotated image for an assessor.
Performance depends on the training data and the conditions under which images are captured. Hidden damage, unusual materials, poor lighting, and severe image distortion can limit reliability, so the app must provide a route for manual inspection.
AI-Based Damage Measurement and Repair Cost Estimation
Depending on the application, image analysis can estimate dimensions, damaged surface areas, or the size of visible defects. Converting those measurements into repair costs requires additional information, including asset specifications, labor rates, parts pricing, regional costs, and insurer-approved estimation rules.
The platform can combine these inputs to prepare a preliminary estimate for review. It should not present an image-derived estimate as a guaranteed final settlement when physical inspection or additional evidence may be necessary.
Integration with Claims and Adjuster Workflows
Measurement results are most useful when they are available in the claim record rather than stored in a separate tool. The app can attach annotated images, measurements, confidence indicators, and estimate details to the relevant case.
Claims handlers and adjusters can then compare the AI-generated assessment with the submitted evidence, correct discrepancies, and document the final decision.
How to Build an AI-Powered Insurance App: From Insurance Workflows to Deployment
AI insurance app development requires coordination between insurance specialists, product designers, software engineers, data teams, and compliance stakeholders. The following steps help translate a business requirement into a deployable application.
Step 1: Identify the Insurance Line and Business Problem
Define whether the app will serve motor, property, health, life, commercial, or another insurance segment. Then identify the operational problem it needs to solve, such as slow claim intake, inconsistent damage assessments, lengthy underwriting reviews, or high volumes of repetitive customer queries.
Set measurable goals before choosing technologies. These could include reducing manual data entry, improving document completeness, shortening a specific processing stage, or increasing the percentage of customer queries resolved without unnecessary handoffs.
Step 2: Map Existing Workflows and Decision Points
Document how information currently moves between policyholders, brokers, assessors, claims teams, underwriters, and external partners. Identify where data is entered repeatedly, where cases wait for approval, and which decisions require licensed or authorized personnel.
This workflow map defines which tasks can be automated, which can be assisted by AI, and which must remain under human control. It also helps prevent the development team from automating an inefficient process without addressing its underlying problems.
Step 3: Define Data Sources and AI Requirements
Identify the data required for each use case, including policy records, historical claims, inspection images, documents, pricing references, and external datasets where permitted. Assess data quality, availability, access rights, and whether the data is suitable for model development.
Next, select the AI approach. Computer vision may be appropriate for image-based assessments, machine learning for prediction, document intelligence for information extraction, and language models for policy-document interpretation. A custom AI model may be necessary when available models cannot meet specific accuracy or domain requirements.
Step 4: Design the App Experience and Human Review Process
Design the interfaces for each user group. Policyholders need clear submission instructions and status updates, while claims teams may need evidence comparisons, exception queues, and review controls.
For AI-assisted decisions, show relevant evidence, confidence indicators where meaningful, and the reason a case was flagged. Define how users can correct information, challenge an assessment, request manual review, or escalate a case.
Step 5: Develop the App and Integrate AI Capabilities
Build the frontend, backend, databases, authentication, and workflow services. Then integrate the selected AI models and connect them to the relevant app features.
For organizations that require tailored models, data pipelines, and intelligent business workflows, AI development services can support the design and implementation of custom AI capabilities. Model selection should be based on the task's accuracy requirements, operating costs, response time, and maintainability.
Step 6: Connect Insurance Systems and External Services
Integrate the app with policy administration, claims management, customer relationship management, document storage, payment services, and third-party assessment tools as required. Use documented APIs, access controls, and validation rules to ensure information moves between systems consistently.
The integration layer should handle failures, duplicate requests, outdated records, and partial updates. For AI agents, access should be restricted to approved actions, with additional authorization for sensitive changes.
Step 7: Validate Accuracy, Security, and Operational Readiness
Test the application with representative data and realistic scenarios. Evaluate extraction accuracy, model performance across relevant customer and asset groups, image-analysis limitations, system response times, and the handling of unusual cases.
Security testing should cover authentication, permissions, data transmission, storage, logging, and access to sensitive records. Before deployment, define acceptance criteria and escalation procedures for outputs that fall below the required standard.
Step 8: Deploy, Monitor, and Improve
Launch the app in stages, beginning with a controlled pilot when practical. Monitor system reliability, user adoption, processing time, exception rates, and the quality of AI-assisted outputs.
Use verified feedback and reviewed outcomes to improve the application. Changes to models, prompts, business rules, or connected systems should be tested before release, especially when they can affect insurance assessments or customer decisions.
Integrating AI Agents with Existing Insurance Systems
AI agent integration can coordinate insurance tasks only when they have reliable access to the information and tools required for those tasks. Integration therefore involves more than connecting a language model to an API; it requires a controlled way to retrieve records, execute actions, and track outcomes.
Core Integration Points
- Policy administration systems: Retrieve approved policy details, coverage dates, and relevant product information.
- Claims management platforms: Access claim status, supporting documents, task assignments, and review outcomes.
- CRM and customer service tools: Retrieve authorized customer context and record interactions.
- Document management systems: Search, extract, and organize relevant policy or claim documents.
- Inspection and estimation services: Exchange image evidence, damage findings, and estimate information where supported.
- Notification and payment services: Trigger approved communications or transactions subject to authorization controls.
API Access, Permissions, and Auditability
Each agent should have a defined scope of access. A claims intake agent may be permitted to create a claim record and request missing documents but not approve a settlement or alter policy terms.
The integration architecture should include identity verification, permission checks, validation, error handling, and logs of actions performed. Sensitive operations may require explicit employee approval, while failed or ambiguous actions should be escalated instead of retried without limits.
How Much Does AI-Powered Insurance App Development Cost?
AI-powered insurance app development can cost approximately $30,000 to $500,000 or more, depending on the scope, complexity of the AI capabilities, integration requirements, and operational controls. A focused application that automates one workflow typically costs less than a multi-line insurance platform with image-based assessments, AI agents, and enterprise integrations.
Estimated Development Cost by Solution Type
| Solution type | Indicative cost |
| Basic AI insurance app with limited functionality | $30,000–$80,000 |
| AI claims automation platform | $80,000–$180,000 |
| AI measurement and damage assessment app | $80,000–$200,000 |
| Enterprise insurance platform with AI agents and multiple integrations | $200,000–$500,000+ |
What Influences the Development Budget?
- AI model complexity: Integrating an existing model for document extraction differs from developing and validating custom models for risk prediction or image-based damage assessment.
- Data preparation: Cleaning historical records, labeling images, mapping policy information, and establishing data pipelines can add significant effort.
- System integrations: Legacy platforms, limited APIs, third-party services, and inconsistent data formats may increase development and testing time.
- Security and regulatory requirements: Identity controls, audit trails, privacy safeguards, model governance, and compliance testing must be factored into the project.
- AI agent capabilities: An agent that answers questions from approved documents has a different scope from one that coordinates tasks across claims, CRM, policy, and payment systems.
- Ongoing operations: Cloud infrastructure, model usage, monitoring, support, security updates, and periodic model evaluation contribute to the total cost of ownership.
A practical estimate begins with a clearly defined first release. Developing one high-value workflow, measuring its performance, and expanding based on validated results can reduce the risk of investing in features that do not improve operations.
Measuring ROI: Where AI Insurance Apps Deliver Business Value
The business value of an AI insurance app should be measured against a documented baseline. Faster processing alone does not guarantee a financial return if the solution creates additional review work, produces inaccurate outputs, or requires expensive manual corrections.
Reduced Claims Handling Time
Track the time between claim submission and key milestones, such as document completion, assessment, routing, and resolution. Compare similar claim categories before and after deployment to understand whether the app is reducing delays.
Lower Manual Processing Costs
Measure employee time spent on data entry, document review, repetitive customer communication, and task coordination. Include the cost of exceptions and manual corrections to avoid overstating savings.
Improved Assessment Quality
For measurement apps, compare AI-generated damage findings and estimates against qualified human assessments. Track material discrepancies, reinspection rates, missing evidence, and the proportion of cases requiring manual intervention.
Better Fraud Investigation Prioritization
Measure how effectively the system identifies cases that merit further investigation. Useful metrics include the proportion of flagged cases that require action, investigation time, and the rate of false positives. A higher number of alerts is not necessarily evidence of better fraud detection.
AI Agent Performance and Customer Experience
Evaluate whether agents complete assigned tasks accurately, reduce unnecessary handoffs, and provide correct answers. Customer satisfaction, repeat contacts, escalation rates, task completion rates, and policyholder complaints can provide additional context.
To calculate financial ROI, compare the verified value of savings and operational improvements with implementation and ongoing costs over a defined period. Results should be based on observed performance rather than assumed automation rates.
Technical Architecture and AI Technologies Behind Insurance Apps
A modern AI insurance application typically combines a user-facing interface, backend services, insurance data integrations, AI components, and security controls. The AI technology choices should reflect the workload and the insurer's existing infrastructure.
- Machine learning: Supports risk scoring, predictive analytics, anomaly detection, and selected forecasting tasks.
- Computer vision: Analyzes vehicle or property images to identify visible damage and estimate measurable characteristics.
- OCR and document intelligence: Extracts fields from forms, invoices, reports, and policy documents.
- Large language models (LLMs): Summarize documents, interpret policy wording, and generate responses grounded in approved information.
- AI agent orchestration: Coordinates multistep workflows, tool calls, task status, and escalation rules.
- Data engineering: Builds pipelines for collecting, validating, transforming, and securely serving insurance data.
- Cloud infrastructure: Supports application deployment, storage, processing, scalability, and system monitoring.
- APIs and integration services: Connect the application with insurance platforms and approved third-party systems.
The architecture may also use retrieval-augmented generation (RAG) services to help language models retrieve relevant information from approved policy documents and knowledge sources. RAG can improve grounding, but it does not eliminate the need to validate responses or control access to sensitive information.
Insurance Data Privacy, Compliance, and Responsible AI
Insurance apps can process personal information, financial records, health-related information, asset images, and claim evidence. Protecting this data is a core architectural requirement, not a feature to add after development.
Protect Policyholder and Claims Data
Apply encryption in transit and at rest, secure authentication, role-based permissions, and controlled retention policies. Limit access to the information required for each task and avoid exposing sensitive data in prompts, application logs, or unnecessary model outputs.
Manage Consent and Data Access
Define what data the app collects, why it is required, who can access it, and how long it will be retained. Use consent and authorization mechanisms where required, especially when integrating external data sources or processing sensitive information.
Reduce Bias and Improve Explainability
Risk scoring and underwriting models can reproduce patterns present in historical data. Evaluate model performance across relevant groups, document limitations, and establish processes for investigating unexpected outcomes.
Where AI influences important insurance decisions, the platform should preserve supporting evidence and make it possible for authorized reviewers to understand and challenge recommendations.
Align with Applicable Insurance Regulations
Requirements vary by jurisdiction, insurance line, data type, and intended use. The project team should identify applicable privacy, insurance, consumer protection, security, and AI-related requirements with qualified compliance and legal stakeholders.
Human review, auditability, and clear escalation routes are particularly important when AI outputs may affect coverage, pricing, claim settlement, or a customer's access to insurance services.
Challenges in AI Insurance App Development and How to Address Them
Incomplete or Inconsistent Insurance Data
AI models depend on accurate, well-structured data to process claims, assess risks, and generate reliable predictions. Missing policy details, duplicate records, and inconsistent claim histories can reduce model accuracy.
Solution: Establish data validation rules, standardize data formats, remove duplicate records, and build data-quality checks into ingestion workflows. Validate training datasets before using them to develop or update AI models.
Integrating with Legacy Insurance Systems
Existing policy administration, claims management, and customer relationship management systems may use outdated architectures or incompatible data formats. This can make real-time data exchange and workflow automation difficult.
Solution: Use secure APIs, middleware, and integration layers to connect AI capabilities with existing systems. Start with high-priority integrations, validate data synchronization, and introduce automated error handling to manage failed transactions.
Inaccurate Damage Estimates
AI measurement apps may misinterpret vehicle or property damage because of poor image quality, unusual damage patterns, hidden defects, or incomplete repair-cost data. Incorrect estimates can lead to additional inspections and delays.
Solution: Implement image-quality checks, train and validate computer vision models using representative images, and combine visual findings with current repair-cost data. Flag low-confidence assessments for manual inspection rather than treating every AI estimate as final.
Unreliable AI Agent Actions
AI agents may misinterpret policy wording, retrieve outdated information, or initiate an inappropriate action when operating across multiple insurance systems. This creates risks for claims processing, customer communication, and policy administration.
Solution: Ground agent responses in approved insurance documents and verified system data. Restrict agents to authorized tools and actions, validate outputs against business rules, and require human approval for sensitive decisions such as claim settlements or policy changes.
Data Privacy and Cybersecurity Risks
Insurance applications handle sensitive customer information, financial records, policy documents, and claim evidence. Weak access controls or insecure integrations can expose this information to unauthorized users.
Solution: Apply encryption, role-based access controls, secure authentication, and data minimization. Maintain audit logs, define retention policies, and test application security throughout development and deployment.
Regulatory Compliance and AI Explainability
AI-generated risk scores, underwriting recommendations, and claim assessments may be difficult to explain or audit. Requirements also vary by insurance type and operating jurisdiction.
Solution: Document model inputs, outputs, limitations, and decision pathways. Maintain traceable records, test for potential bias, and involve compliance specialists when defining workflows. Ensure that AI-assisted decisions follow applicable insurance and data protection requirements.
Why Choose Suffescom for AI-Powered Insurance App Development?
Building an AI-powered insurance app requires more than adding a chatbot or integrating a predictive model. The solution needs to fit insurance workflows, connect with relevant systems, protect sensitive information, and provide a reliable experience for policyholders and employees.
Suffescom develops custom software and AI-enabled applications around defined business requirements. For insurance organizations, the development scope can include digital insurance platforms, claims workflow automation, AI-based document processing, image assessment capabilities, and AI agents designed to coordinate approved tasks.
The project approach can cover requirements analysis, solution architecture, application development, AI integration, system testing, deployment, and ongoing improvement. The technology and implementation plan should be selected according to the insurance product, existing infrastructure, data availability, and required level of automation.
Organizations evaluating digital insurance capabilities can review Suffescom's insurance software development solutions to understand the broader service area. The focus should remain on identifying a practical use case, validating the expected operational value, and building a platform that can evolve as insurance requirements change.
FAQs
What is an AI-powered insurance app?
An AI-powered insurance app uses artificial intelligence to support tasks such as policy assistance, risk analysis, document processing, claims handling, fraud detection, and customer service. Its capabilities depend on the insurance workflow and the data and systems available to it.
How does AI automate insurance claims processing?
AI can extract information from claim forms and supporting documents, identify missing information, summarize case details, and route claims according to defined criteria. Workflow automation can handle approved routine tasks, while complex or sensitive decisions can be escalated to claims professionals.
How does an AI insurance measurement app estimate vehicle or property damage?
The app analyzes submitted images or videos to identify visible damage and, where the model supports it, estimate dimensions or affected areas. It can combine these findings with asset information and repair-cost data to prepare a preliminary estimate for review. Accuracy depends on image quality, model validation, and the availability of reliable cost information.
What can AI agents do in insurance?
AI agents can coordinate tasks such as collecting claim information, checking document completeness, retrieving policy details, preparing summaries, responding to routine queries, and following up on outstanding requirements. Their permissions should be limited, and important decisions should follow the insurer's approval and compliance processes.
Can AI insurance apps integrate with existing claims management systems?
Yes. AI insurance apps can connect with claims management, policy administration, CRM, document storage, payment, and third-party assessment systems through APIs or other supported integration methods. The available interfaces, data formats, security requirements, and legacy infrastructure influence the integration effort.
How much does it cost to develop an AI-powered insurance app?
A focused solution may cost approximately $30,000–$80,000, while more complex claims automation or measurement platforms can cost $80,000–$200,000. Enterprise platforms with AI agents, extensive integrations, and advanced controls can exceed $500,000. These are indicative estimates; the actual budget depends on scope, data readiness, model complexity, and integration requirements.
How long does it take to develop an AI insurance app?
A focused application may take a few months, while a complex platform with custom AI models, legacy integrations, and extensive validation can take considerably longer. The timeline depends on the feature scope, availability of data, integration complexity, testing requirements, and regulatory review.
How can insurers measure ROI from AI agents and claims automation?
Insurers can compare baseline and post-deployment metrics such as processing time, manual effort, cost per claim, document completion rates, exception rates, customer satisfaction, and model accuracy. ROI calculations should include implementation expenses, ongoing operating costs, and the cost of errors or manual review.
How can AI improve insurance fraud detection?
AI can analyze patterns across claim histories, documents, transactions, and other authorized data to identify anomalies for investigation. The system helps prioritize suspicious cases, but flagged activity requires appropriate verification because unusual patterns do not automatically establish fraud.